


Want to leave an inheritance? Here’s why you might want to consider ‘giving while living’


For many people, leaving an inheritance isn’t just a happy side-effect of having money left over when you die.
Instead, it’s carefully planned, setting wealth aside to support family, friends or charitable causes, when you pass away.
It’s understandable to want to use your hard-earned money to provide for your loved ones once you’re no longer here.
But while there’s nothing wrong with this strategy, have you considered gifting your money in your lifetime instead?
The chance to see the impact your money could have
Rather than leaving an inheritance, you could consider ‘giving while living’ and passing on wealth while you’re still alive.
That might give you the opportunity to put your money into your loved ones’ hands when it matters most to them.
For example, your money could help your children or grandchildren to:
If you wait until you die to pass down your wealth, your family might be funding these goals for themselves. There’s a risk they could miss out on achieving them, too.
Meanwhile, giving them money now - especially funds you already plan to pass to them when you die - could help ensure they reach those targets.
Not just that, but the real reason you’re setting money aside for their future inheritance is so they can get the things they want out of life.
By giving them access to that money now, you can have the satisfaction of watching them make the most of it.
There could be financial benefits to giving while living
Giving while living doesn’t just mean you can enjoy seeing your loved ones use your money to achieve their financial goals during your lifetime.
It might also come with financial benefits that mean your chosen beneficiaries pay less tax, leaving them with more of your money.
When you die, your estate - that’s your money and assets, all totalled up - could face Inheritance Tax (IHT). That’s the case if your estate exceeds certain thresholds. In 2026/27:
If your estate exceeds these thresholds when you pass away, your loved ones could face a 40% tax charge on that portion of your wealth. So, they might get less than you expect if you’ve kept money back to pass to them.
But some types of gifts you make in your lifetime can fall outside the value of your estate. In 2026/27, you can:
Using these various thresholds and rules could allow you to pass money to your family without facing a tax charge. And, it could reduce the overall value of your estate, cutting down the bill they’d face on your death.
With pensions set to come into the IHT net from April 2027, more of your money could be taxable on your death. Making these gifts could help your loved ones reach their goals while reducing an IHT charge.
{{main-cta}}
Make sure you can afford to gift during your lifetime
It makes perfect sense to want to help loved ones financially, either now or when you’re no longer here. But when doing so during your lifetime, it’s worth making sure that you’re not gifting money that stops you from reaching your own goals.
Otherwise, you could end up giving away the funds that you’ve saved throughout your life for your dream retirement.
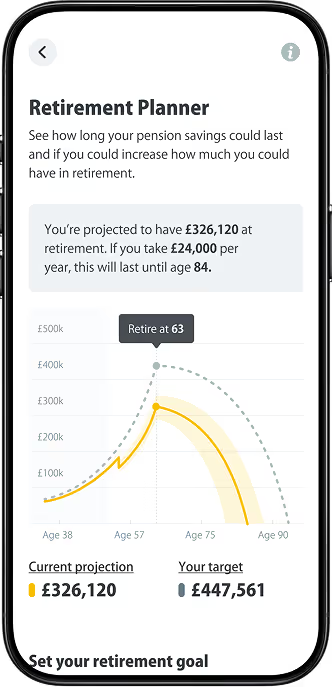
PensionBee’s Pension Calculator could help here. You can input how much you’re saving and how much you want to have in retirement.
The calculator can then show you a projection of how much you might have in later life. Plus, you'll get an idea of how long it’ll last, depending on your desired retirement age and income.
With this information to hand, you can compare what you have now with what you’re projected to need.
That can give you greater confidence that you can afford to make gifts now without hurting your own financial security and wellbeing.
Risk warning
As always with investments, your capital is at risk. The value of your investment can go down as well as up, and you may get back less than you invest. This information should not be regarded as financial advice.
Please note that tax rules change regularly, and the actual tax benefits you receive will depend on your individual circumstances. If you’re not sure, please seek professional advice.
Period | Market Event | FTSE World TR GBP (%) | 4Plus Plan (%) |
|---|---|---|---|
4Plus Plan’s inception – 6 Sept 2013 | QE Tapering, China Interbank Crisis and its aftermath | -5.44 | -2.41 |
3 Oct 2014 – 15 May 2015 | Oil price drop, Eurozone deflation fears & Greek election outcome | -5.87 | -1.77 |
7 Jan 2016 – 14 Mar 2016 | China’s currency policy turmoil, collapse in oil prices and weak US activity | -7.26 | -1.54 |
15 June 2016 – 30 June 2016 | BREXIT referendum | -2.05 | -1.07 |