




The following is a transcript of a bonus podcast episode of The Pension Confident Podcast. Listen to the episode, watch on YouTube or scroll on to read the conversation.
PHILIPPA: Hi, welcome to our ‘Behind the Pension’ series. This time we’re going to hear from Joumana.
JOUMANA: I wish when I’d arrived in this country, there was a little booklet that says, “Here’s how things work financially here”, and then I would’ve looked into it. But I didn’t even know it was a possibility to open a personal pension.
PHILIPPA: This series is about listeners like you telling us all about their pension stories. Joumana is a freelance Artist. She’s based in Oxford, and she explains how confusing she found the British pension system when she migrated here from Lebanon 13 years ago. She tells us what it took to make her start saving, why she thinks the self-employed pension gap is so important, and what she wants her retirement to look like.
I’m Philippa Lamb, and if you haven’t subscribed to The Pension Confident Podcast yet, click that button right now so you never miss an episode.
PHILIPPA: Pensions expert, Dani Skerrett, from PensionBee is here with me. Hi Dani.
DANI: Hi Philippa.
Meet Joumana
PHILIPPA: Let’s meet Joumana.
JOUMANA: So, I’m Joumana, I’m 46 [years old], I’m an Artist and Independent Researcher and currently based in Oxford. So, other than the tax contributions to [the] State Pension, I only started saving to my own pension last year. So not a very long time ago because I didn’t know anything about pensions.
When somebody comes and settles, and particularly when they get British citizenship, if there was a financial help guide, saying “This is what you can do with your money”, because a lot of people who arrive have no idea. I would’ve loved to have started saving for my pension when I arrived, even if it was tiny sums at first. At one point I was - I had an option to buy some National Insurance years that were missing. It was quite a big sum for me to pay at the time, and I was wondering, “Is it worth it, is it not worth it?”. And in the end, I did buy them back. It was still enough to get me to say, “OK, well, it might make a little difference, so let’s just do it”.
PHILIPPA: So, Joumana started saving into a personal pension in her mid-40s, it wasn’t a case of putting it off, was it? She genuinely didn’t really know it was an option. How common is that Dani? That late start, particularly maybe amongst people who’ve moved here from abroad?
DANI: I think it’s very common to find the pension system confusing, which puts you off starting. Even if you’re British and you’ve grown up here and you’ve gone to school in Britain and your parents have saved into pensions. It’s confusing then. So, if you’ve moved from abroad, [it’s] even more confusing. So, I do feel for Joumana, but she’s not on her own. I think it probably feels quite lonely and scary, but there’s data from the Department of Workplace and Pensions, the DWP, which says one-in-four people from age 40 to 75 have no private pension.
PHILIPPA: That’s a big number.
DANI: It’s a big number. I guess we could presume they might have a workplace pension, they might have property, they might have inheritance coming their way, so perhaps they have a plan, but they don’t have a private pension at all.
PHILIPPA: Yeah
DANI: And that’s a big age gap, 40 to 75.
PHILIPPA: It is.
DANI: And it’s really actually the time you start thinking about your retirement fund, probably post-40 [years old].
PHILIPPA: Yeah, so she’s not alone.
DANI: No, she’s not alone. She also mentioned she’s freelance, so she falls under that self-employed worker -
PHILIPPA: yeah -
DANI: so, any freelancer or contractors or business owners will feel the same as her in that it’s much more difficult to think about your pension savings.
PHILIPPA: Because yeah, Auto-Enrolment, of course, that only covers employees.
DANI: Yeah, exactly. We talk about Auto-Enrolment quite a lot and what an amazing thing it is, and it has been a game changer for a lot of full-time and part-time employed workers. So, people that are on PAYE. But it doesn’t include self-employed people.
PHILIPPA: I mean, when you think self-employment can be quite fragile anyway.
DANI: Yeah, it can. It’s up and down, isn’t it? You’re wearing so many hats already, and then you have to also be your financial planner, your own accountant, your own retirement expert. So, it’s tricky, but there’s a silver lining, and actually it’s never too late to start.
PHILIPPA: Yeah, the key thing is to start, right?
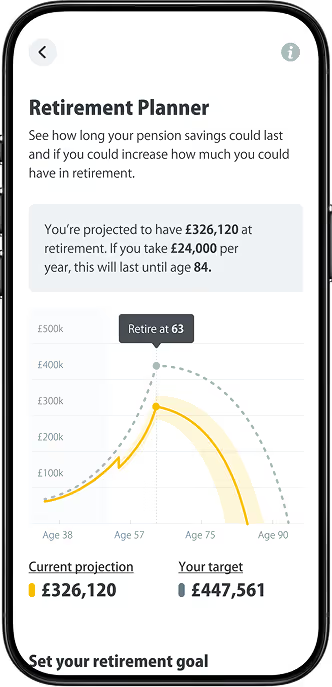
DANI: The key thing is to start, and there’s loads of tools online that you can use to forecast. We have a brilliant calculator on the PensionBee website, our Pension Calculator, and you can play around with the figures, and it really brings to life that actually, if you’re thinking about someone that’s 40 years old, they’re at least 20 years away from thinking about retiring around 60 [years old] -
PHILIPPA: yeah -
DANI: I think a lot of people see 60 as [their] retirement age, don’t they? Or winding down.
PHILIPPA: It’s getting older, isn’t it? Because we’re living longer.
DANI: It’s getting older. And I think [the] State Pension age at the moment is 66 [years old] but that’s rising from April 2028. So that’s getting older. And so, if you’re using that as a marker, if you’re [age] 40, you’ve got [over] 26 years.
PHILIPPA: So, say you began even later, say you began at [age] 50 and you were saving, I don’t know, £400 a month -
DANI: yeah -
PHILIPPA: where would that put you?
DANI: Yeah, so using the Pension Calculator, if you’re saving £400 a month, and don’t forget when you save into most defined contribution pensions, which most private pensions are these days and workplace pensions, you get a government tax top up. They reward you for paying into your pension. So, if you’re putting in £400 a month, it actually gets topped up to £500 a month.
PHILIPPA: Which is amazing, isn’t it? 25% tax top up from the government.
DANI: Yeah, and that’s for basic rate taxpayers. So, you might be owed more tax relief if you’re higher and additional [rate taxpayer]. But let’s just talk about basic rate taxpayers.
PHILIPPA: So, you’re paying £400, the government’s giving you another £100 -
DANI: they’re topping up to £500. So, your £500 that’s going in, and then assume potential investment growth of 5%, which is modest. After 20 years, you could have a pot of around £200,000.
PHILIPPA: Yeah, which is worth having.
DANI: Definitely worth having. And then you can also use our [Pension] Calculator to see then how much income that might give you in retirement.
PHILIPPA: OK, so what sort of money would that be every year?
DANI: So, you could - that could give you roughly £8,000 a year.
PHILIPPA: And that’s on top of the State Pension?
DANI: Yeah, so if you’re already eligible for the [full new] State Pension, you’re getting, I think it’s around £12,500 a year (2026/27).
PHILIPPA: Yeah. So that would take you to what, more than £20,000 a year? -
DANI: yeah -
PHILIPPA: from age 70 -
DANI: taking it from age 70. So, it’s - that’s a rough calculation, but it gives you a bit of a benchmark as to then you could think, “OK, well, what would happen if I put another £50? What would happen if I started taking my pension at [age] 75?” -
PHILIPPA: yeah -
DANI: give yourself another five years for potential growth -
PHILIPPA: absolutely. Or if you pulled the age at which you start earlier if you can, great -
DANI: exactly -
PHILIPPA: and that all helps, doesn’t it? -
DANI: yeah.
PHILIPPA: Missing National Insurance years is a problem too, isn’t it, for a lot of self-employed people? Because obviously this is what entitles you to your State Pension -
DANI: yeah -
PHILIPPA: and people who spent time abroad, I think they may have that problem too, don’t they? You can buy them back, can’t you, the lost years?
DANI: You can. It sounds more complicated than it is, I think. The key thing is that all the information you need is on the government website, so it’s just setting aside the time to sit down and do your calculations and see where you’re up to. So, State Pension eligibility, you need 35 years of qualifying National Insurance contributions. [It’s] worth going on to the government website and having a look at your National Insurance record, which will tell you how long you’ve been paying them and how many years, qualifying years, you have.
PHILIPPA: Yeah, that’s very easy to do. I’ve done that myself. It’s extremely straightforward. Just jump on the website and you can see if you’ve got gaps. It shows you where they are -
DANI: yeah -
PHILIPPA: and of course, a lot of people do have gaps, don’t they? You might be abroad, career break.
DANI: Well, this is the thing. We’re talking about 35 qualifying years, and you might hear that and think, “Well, I’ve worked for 35 years”, but what if you’ve taken time out during a year? What if you’ve raised a family and taken multiple years off?
PHILIPPA: Or self-employment, when you start out, a lot of people forget about National Insurance contributions.
DANI: Exactly. And you might be earning slightly lower than the limit at some points, like if - yeah, there’s loads of different reasons why gaps can occur. So definitely go to GOV.UK and check your forecast, and it’s free, and you can just see where you’re at from there. Joumana spoke about filling the gaps -
PHILIPPA: yeah -
DANI: so, you can do this, you can make - they call them voluntary contributions.
PHILIPPA: So, you can only go back and fill in the payments that you’ve missed from a certain number of years though, right?
DANI: Yeah, six years.
PHILIPPA: And it’s well worth doing, isn’t it?
DANI: Yeah, the gaps are [usually] worth filling. So, most people will buy back a Class 3 National Insurance contribution, and that works out at £18.40 a week or £956.80 a year.
PHILIPPA: OK.
DANI: You could be eligible to buy back the cheaper Class 2 rate. Some self-employed people might qualify for this. It depends on how much you earn. So, to buy back the Class 2 National Insurance years, it’s £3.65 a week or £189.80 a year.
PHILIPPA: OK, so a lot cheaper.
DANI: Yeah.
PHILIPPA: OK.
How your pension is protected
PHILIPPA: Now, Joumana, she has a very specific reason for not wanting to bet everything on any single financial plan, doesn’t she? And it’s rooted in something that she saw back home in Lebanon.
JOUMANA: I’ve just seen it in my own country a few years ago where everybody’s bank accounts vanished overnight. Like, they’re gone. All the - everything’s gone. All the savings, zero. Nobody has anything left. And it’s just inconceivable. But I didn’t even know it was a possibility to open a personal pension and that it was a good idea and that the State Pension would probably not be enough, etc. I had no idea. I’ve come from a country where there was no such thing. [The] system was very shambolic and nobody explained anything. It never occurred to me that it’s something I should think about. So, I had to learn everything about it. And I wish when I had arrived in this country there was a little booklet that says, “Here’s how things work financially here”.
PHILIPPA: I think we could all do with that book, right? Because she’s not alone in that regard. And that fear she has about, investing her hard-earned money in a fragile financial system that might just collapse. I think it’s completely understandable, isn’t it? I think a lot of people here, even though we think we have a better protected system, I think people do worry about that, don’t they?
DANI: They do. There’s a lot of mistrust in financial services, especially complex financial products like investments and pensions -
PHILIPPA: yeah -
DANI: where it’s not as simple as understanding your bank account and saving into a bank account. There’s a lot of mistrust. So yeah, I think a lot of people can relate to Joumana’s fears.
PHILIPPA: So how protected, if we’re talking about pensions here in the UK, how protected are you, in law and by regulation?
DANI: So, if we’re just talking about defined contribution pensions, which most modern workplace and private pensions are, it’s probably simple to just talk about that. And this isn’t the State Pension, that’s an entirely different thing.
So, if you’ve got a workplace pension or private pension savings, they’re regulated by the Pensions Regulator and the Financial Conduct Authority, the FCA. So, your employer, your workplace, will pick a provider to invest money in for your pension. So, the money you’re paying into your workplace pension isn’t actually with your employer, it’s held by the [pension] provider. So, that could be, yeah, a number of different, of different names. If we take PensionBee, for example -
PHILIPPA: yeah -
DANI: if you’ve got a private pension with PensionBee, the money isn’t held with PensionBee, it’s held separately by big asset managers. So, these are companies like BlackRock, State Street, Legal & General, and those money managers are regulated. So, they’re the ones with your money, and you’re also protected by the Financial Services Compensation Scheme (FSCS) with most private pensions and workplace pensions, and they’ll cover up to 100% of your claim.
PHILIPPA: And this is about providers going down, this is about fraud, this is about all the bad things that we think about in the middle of the night.
DANI: Exactly.
PHILIPPA: What it doesn’t cover you for - we do need to make this clear. Yeah, it doesn’t, it doesn’t cover you for market losses.
DANI: No, of course not. This is, you know, your investments are [usually] within the stock market, and they can go up in value, they can go down in value, and, and you’re not covered for that. That’s [an] investment risk that everybody’s taking. But if your employer goes bust, again thinking about a workplace pension with an employer, it’s actually the pension provider that holds your money -
PHILIPPA: yeah -
DANI: it’s not the employer.
PHILIPPA: Yeah, and you’re covered by the scheme.
DANI: You are.
PHILIPPA: It’s probably worth saying at this point that if you have a Self-Invested Personal Pension (SIPP), which is a different sort of pension. The rules are different, aren’t they?
DANI: Yeah, it’s slightly different. You can only claim up to £85,000 in that situation, but the FSCS website has all the information.
PHILIPPA: Yeah, so check.
DANI: So, you can find out what type of pension you have, who it’s with, and what you could be compensated with.
PHILIPPA: Got it.
PHILIPPA: There’s a new Prime Minister in Number 10, and his new Chancellor has a big Statement to deliver this autumn. Stay in the loop with what you need to know, especially when it comes to pensions, by subscribing to The Pension Confident Podcast.
Self-employed pension contributions
PHILIPPA: Now, getting back to Joumana, she’s freelance, as we’ve said, and obviously that means her income doesn’t arrive in neat monthly instalments. That does make pension saving more complicated, doesn’t it?
JOUMANA: So, because I’m a freelance artist, the work’s a bit feast or famine. So, you have very good years and then you have years where there’s nothing. And when you barely are getting enough to get by, putting money away that you can’t touch for another decade or two isn’t feasible. I picked a slightly risky plan because I have time and at this point, I’m still happy to go with it. But I was saving more in the beginning because I had more spare cash. And right now, I’ve stopped contributing temporarily until things pick up again.
PHILIPPA: I think Dani, a lot of self-employed people are going to recognise what she’s just said -
DANI: yeah -
PHILIPPA: I mean, it’s all very well saying you should always contribute, but there’s only so much money. Let’s talk a bit about the options for someone with a variable income. I mean, how flexible are personal pensions in terms of contributions? Do you have to contribute the same amount every month?
DANI: Yeah, I think flexibility is key, like you just mentioned. So, finding a provider where you can contribute as little as you can each month, especially if your income is variable. So, with PensionBee, we have completely flexible contributions, you could pause them, as Joumana mentioned. But what we like to say when we talk about self-employed workers is dial it down -
PHILIPPA: rather than stop completely -
DANI: rather than stop completely, because then it’s much harder to start back up. Obviously, everybody’s situation is different, so there might really be times where you can’t put a single penny in. But if you’re talking about variable income, so say one month you’re used to a couple of thousand pounds, the next month it’s only £1,000, just think about it in a percentage instead of a number and just dial down the amount based on what that percentage is. So, if you always say that you do 10%, then 10% of whatever income that was that month.
PHILIPPA: Even if it was a small income that month.
DANI: Yeah, even if it was much less.
PHILIPPA: Yeah, that’s quite a nice way of thinking about it, isn’t it? Because as you say, if you stop it completely, well, we forget, don’t we? Because life is busy. And as you say, start it up again, it feels like a task, doesn’t it?
DANI: It does. And just think about putting as little as you can in, in that sense. And then at least that payment is still coming out and you’re used to the habit of seeing that leave your account and you’re safe in the - you feel safe that you’re still putting something away.
PHILIPPA: Now, more optimistically, if you’re earning a lot of money and it’s a great year as a freelancer -
DANI: absolutely -
PHILIPPA: there’s a limit, isn’t there, on how much you’re allowed to save?
DANI: Yeah, so opposite end of the spectrum with self-employed people thinking about chucking in as much as you can, it’s great, up to a limit. So, there’s the annual allowance and now this is the limit on the gross amount that you can save into a pension a year, into your private pension -
PHILIPPA: and how much is that? -
DANI: personal pension or a SIPP, and that’s £60,000 (2026/27)
PHILIPPA: OK, so every year the maximum amount you can do is £60,000 a year because otherwise you get involved in tax charges, don’t you?
DANI: Exactly, yeah, that’s without incurring tax charges. So just be aware that that’s the limit. You can put in more, but there’s tax complications, and yeah, just think of that as your ceiling. Before things get complicated.
PHILIPPA: So, what about Joumana’s point about choosing a higher-risk pension plan?
DANI: Yeah, generally, the longer your time horizon, the more risk you can take with your plan. So, where we make the point about starting early, for people in their 20s and 30s and sometimes even in your 40s, like, you might want to take a slightly higher-risk plan. That could mean you’re invested more in the stock market, which is more - which can fluctuate and which can experience volatility and which can go up and down, but there’s also the possibility of it going up.
PHILIPPA: So, your losses might be bigger, but your gains might be higher as well -
DANI: yeah -
PHILIPPA: and you can ride it out because you’re a long way off actually taking your pension.
DANI: Exactly. If you have a couple of decades, then over a five year period, if there’s some dips and some peaks, then you can just think, “Well, I’ve still got 20 years to go for it to all iron out”.
PHILIPPA: Yeah, as you say, I mean, that is, it’s a very individual decision, that, and all about how much appetite you feel for risk, isn’t it?
DANI: It is, yeah, and when you want to start taking your money. Some people might be listening thinking, “Well, I want to take it at 50 [years old]”, in which case, in your 40s, you [might] need to start thinking about taking less risk.
PHILIPPA: Yes, because you don’t want to jeopardise it.
DANI: Yeah.
The Retirement Living Standards
PHILIPPA: So, what might retirement look like for Joumana?
JOUMANA: You know, discussing money is a taboo subject in Lebanon. It’s just not done. You don’t talk about it. It’s not - it’s a bit indecent. My American partner, he surprised me the other day [by] thinking, “So where should we buy a house for our retirement?” I mean, that’s like 35 years away, right? And I’m like, “I haven’t thought about it, but I’m happy to talk about it”.
I come from a place of massive uncertainty. And I can’t, I don’t know what’s going to happen one year to the next. Completely diametrically opposed worldviews. I don’t imagine retiring in the sense of stopping to do my job, but I’d really love a house that is paid for and knowing I can always pay my bills, and I can just continue doing my work without worrying. Peace from insecurity. That’s basically all I’m after. And my boyfriend with me.
PHILIPPA: “Peace from insecurity”. I’ve got to think that chimes with a lot of people. It’s a really honest description of a retirement goal. Maybe it’s the first we all think of, isn’t it? We just don’t want insecurity.
DANI: Yeah, definitely. I think when we think about retirement and pensions and numbers, it can get quite overwhelming and a bit abstract. But actually, I think if you try and think about how you want your life to be, how it’s going to make you feel having that fund, that retirement fund, that’s a better place to start from, and then you can work backwards. If you’re thinking, “Well, I want to carry on working, I want to be active, I want to do this and that, I want to spend time with family”, OK, maybe you don’t need quite as much. But if you’re thinking, “Well, I want to finish work, I don’t like my job, or I don’t want the stress of working, so I don’t want to be working at all”, well, you’re going to need a much bigger pot. So, start with what you want your life to look like and work backwards is a great way to think of a retirement goal.
PHILIPPA: Yeah, and it’s like she said, that thing of, I want to be sure that I’ve got somewhere to live -
DANI: yeah -
PHILIPPA: and I want to be sure I can pay my bills -
DANI: yeah.
PHILIPPA: It seems like a good place to start, and everything else beyond that is jam on top, isn’t it?
DANI: It is, yeah, exactly. We talk about the Retirement Living Standards a lot. This is a set of figures from Pensions UK which show you what your life could look like at three different income levels. So, they base it on a year’s worth of expenses for either a single person or a couple; at either a minimum, a moderate, or a comfortable lifestyle, and they put different things against it. So how many holidays you might be able to have, how much you could spend a week on groceries. So, it’s a really good benchmark of, “OK, what am I looking at for like an annual income, and what would that get me?”.
PHILIPPA: Yeah, because it’s hard to visualise how much money you’re going to need, isn’t it?
DANI: It’s really hard to visualise.
PHILIPPA: They update the numbers, don’t they, annually?
DANI: Yeah, so these come out every year.
PHILIPPA: Where are they now then [in 2026]?
DANI: So, if we just look at the moderate standard, that’s somewhere in the middle. For a single person, you’d need £32,700, and if you’re in a couple, £45,400.
PHILIPPA: And this is annual income?
DANI: This is annual income, and crucially, they take into account that you’ve already either paid off your mortgage or don’t have any rent costs, so you don’t have any housing costs.
PHILIPPA: Yeah, see, I always think that’s really, really key to say because, you know, for a lot of people, that’s a huge part of what you spend every month, isn’t it?
DANI: Yeah, because if you think £32,700 on your own, that’s quite a nice annual income, but not if you’ve got [a] £2,000 mortgage every month -
PHILIPPA: yeah -
DANI: but we’ve just recently done some calculations and we’ve looked at - because again, these numbers can sound quite abstract, so £32,000 a year, but how do you know how much you need to have saved at each age to -
PHILIPPA: achieve that -
DANI: achieve that eventually, like, what’s the final pot? So, we’ve looked at a 30-year-old, a 40-year-old, a 50-year-old, a 60-year-old -
PHILIPPA: OK -
DANI: to see if you’re on track for that moderate living standard, how much you’d need in your pension pot during those ages.
PHILIPPA: Oh, that’s really helpful, isn’t it?
DANI: Yes, exactly.
PHILIPPA: So, you actually understand what you’re aiming at.
DANI: Exactly. That can help bring it into real terms a bit more. And then, like I mentioned, you can use the PensionBee Pension Calculator to put that number in, put your retirement age in, and see how much, adjusting your contributions, making them a bit higher, making them a bit lower if you need to, can help you get there.
PHILIPPA: And Joumana, she’s - she obviously, she’s still working away at this, isn’t she? But she has done the hard bit, hasn’t she, already?
DANI: Yeah, I mean, even just thinking about it and having a look at your situation and having a look at your National Insurance contributions and how much State Pension you might be entitled to, saving into a pension at all. You know, she’s engaged, and that’s, I think, for a lot of people, the hardest part.
PHILIPPA: Yeah, because she’s got a plan, she’s comfortable with. She’s bought back her National Insurance years -
DANI: Yeah -
PHILIPPA: She knows what she’s aiming at -
DANI: She does, yeah. And it’s just thinking about it, like, don’t put it off for too long, starting to think about what you want your life to look like, because the sooner you start thinking about it, the sooner you can put a plan in place to help you get there. I think, like, just taking control is the hardest first step, but once you’re over that, you’ll feel much better about using these tools and starting to play around with your contributions, but it really is like getting over that. that fear that you’re not in control of it. Once you get over that first step, there’s power in knowledge.
PHILIPPA: There is, isn’t there? So, if someone’s listening to this and that is them, we’re saying they should go to the government website, right?
DANI: Yeah.
PHILIPPA: And, and see what’s happening with their National Insurance contributions, and they should go to the PensionBee website and look at the knowledge zone on there, shouldn’t they? Because this isn’t about selling you PensionBee products, it’s just about you understanding what goes on with pensions, right?
DANI: It is, yeah, and just understanding where you’re at. So, check your State Pension forecast using the government website and then use the PensionBee website, like you said, our blogs, our different podcast episodes and videos to understand where your pensions are, what your position is.
PHILIPPA: And what your options are.
DANI: And what your options are, yeah.
PHILIPPA: Thanks, Dani.
JOUMANA: Thank you.
PHILIPPA: Thanks to Joumana too for sharing her story with us. If you’d like to find out more about pensions and retirement planning, as we’ve said, head to the show notes for this episode, go to the website. We’ve shared a tonne of resources there for you to explore, and you can just use them for yourself, see what you think.
Here’s that final reminder before we go, that anything discussed on the podcast shouldn’t be regarded as financial advice or as legal advice, and when investing, your capital is at risk. Thanks for being with us this time. We’ll see you next time.
Risk warning
As always with investments, your capital is at risk. The value of your investment can go down as well as up, and you may get back less than you invest. This information should not be regarded as financial advice.
Period | Market Event | FTSE World TR GBP (%) | 4Plus Plan (%) |
|---|---|---|---|
4Plus Plan’s inception – 6 Sept 2013 | QE Tapering, China Interbank Crisis and its aftermath | -5.44 | -2.41 |
3 Oct 2014 – 15 May 2015 | Oil price drop, Eurozone deflation fears & Greek election outcome | -5.87 | -1.77 |
7 Jan 2016 – 14 Mar 2016 | China’s currency policy turmoil, collapse in oil prices and weak US activity | -7.26 | -1.54 |
15 June 2016 – 30 June 2016 | BREXIT referendum | -2.05 | -1.07 |