Frequently Asked Questions
Showing all 87 questions
No questions match that search. Try a different word, or contact our UK team.
About the PensionBee service
Does PensionBee have an app?
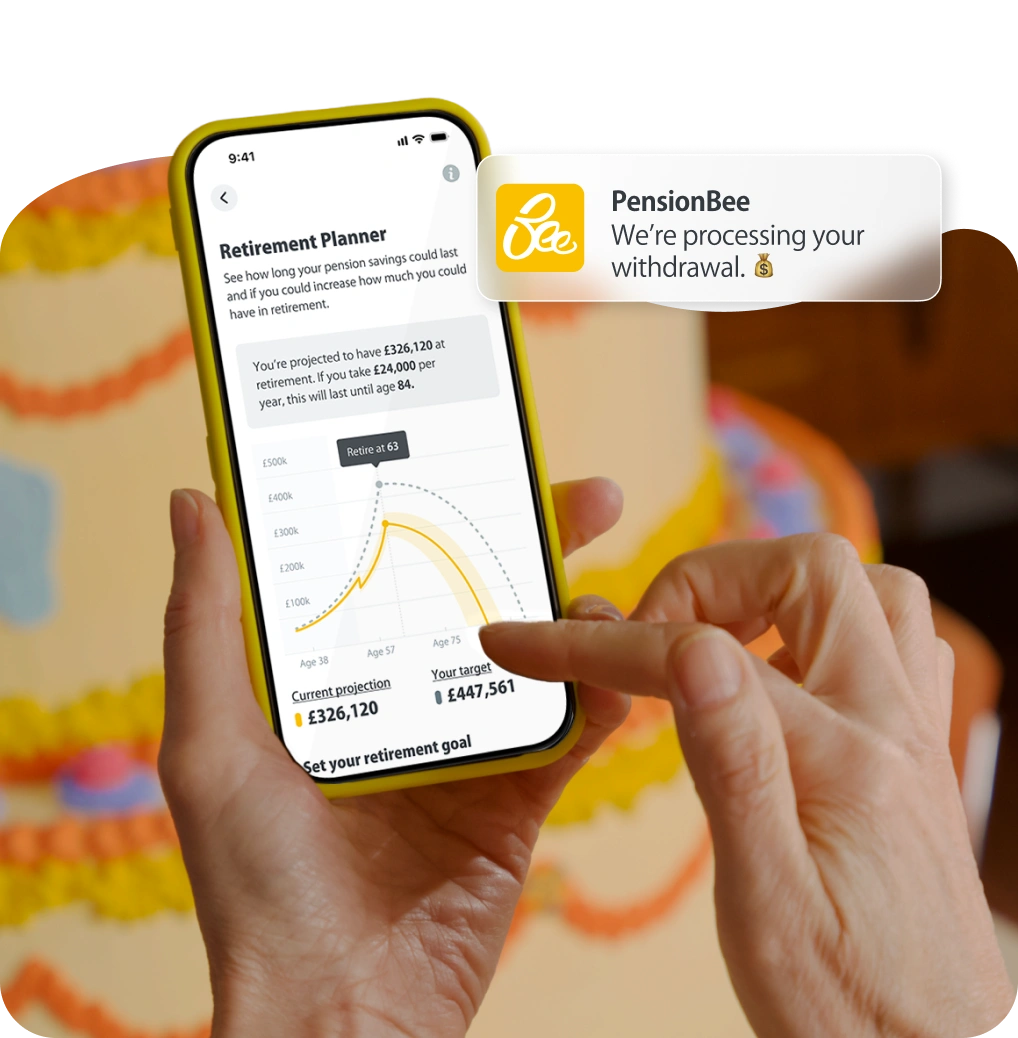
Yes, we do! Our mobile app's available for existing customers in the App Store and Google Play stores, and you can use it to access your real-time pension balance with PensionBee, without needing to log into your online account (known as your 'BeeHive') through a web browser.
What does PensionBee do?
We're on a mission to build pension confidence and put savers in the UK and the US in control of their retirement savings. Through our award-winning app, we make accessing your pension straightforward. It's easy-to-use and allows you to withdraw with ease from age 55 (rising to 57 in 2028).
In the UK, PensionBee combines your old workplace pensions and transfers them into one new online pension plan, managed by some of the world's largest money managers. If you don't know exactly where your old pensions are, you can contact your former employer or use the government's free Pension Tracing Service. Or, if you're self-employed, you can set up flexible pension contributions as a sole trader or director of a limited company. Contribute as much or as little as you like, as often as you like.
The 'BeeHive' is a customer's online account. Inside the BeeHive you can contribute to your pension. Our app makes accessing your pension straightforward. It's simple-to-use and allows you to withdraw with ease from age 55 (rising to 57 in 2028). You'll be able to view your live pension balance and see your projected retirement income.
In the US, we help our customers to combine their retirement savings into a new online account, which they can manage from the palm of their hand. Our technology platform makes it easy for customers to consolidate their 401(k)s and IRAs into one diversified online plan, so they can take the first step towards financial freedom.
We create calculators and retirement forecasting tools to help our customers plan ahead, enabling them to build a clearer picture about what they should be contributing. Then, when they reach the age of 59 and a half, we make it simple for our savers to make on-demand and appropriate withdrawals.
Is PensionBee a Self-Invested Personal Pension (SIPP)?
A SIPP, or Self-Invested Personal Pension, is a type of pension that allows you to choose your own specific investments, including individual stocks and shares. You can manage your investments yourself or with the help of a financial adviser.
PensionBee offers a personal pension that allows you to select your own investment plan from our range of diverse and curated plans.
We've partnered with some of the world's biggest money managers, predominantly BlackRock and State Street, to provide our investment choices. This style of investing may be suitable for people who prefer a hands-off approach to pension saving.
Can PensionBee trace my pension for me?
While we'll do everything we can to help you transfer your pensions, we can't trace your old pensions for you. You'll need to provide us with your policy number when transferring from certain providers. If you don't have it handy, we recommend giving your current provider a call or reviewing past communications from them.
You'll be asked to input this information as part of our sign up process. If you have any further information that might be useful to us, you can add it in your online account (known as your 'BeeHive') at any time. The more information you can give us, the easier it'll be to speak to your old provider, and transfer your money.
If you don't know this information, you'll need to use the government's free Pension Tracing Service. Without the right information about your old pensions, we can't start a transfer from your old provider to PensionBee. You can check whether you're likely to have a pension by answering a few simple questions on our Do I have a pension? page.
Why should I consolidate my pensions with PensionBee?
If you've had several different jobs then you probably have different pension pots scattered around. Most pension providers send a lot of paperwork that can be difficult to understand and contains hidden fees that can reduce the value of your pension. This makes it pretty difficult to keep track of your retirement savings and plan for the future.
PensionBee exists to make managing your pension easier. If you combine your pensions with PensionBee, and we discover that an old pension provider charges an exit fee of more than £10, or that your pension comes with special benefits or guarantees, we'll ask your permission before we complete the transfer.
With PensionBee, you can access your pension easily through our award-winning app, meaning your pension is at your fingertips. You can see your current pot size, your projected retirement income, and set up regular or one-off contributions. Your dedicated account manager (known as your 'BeeKeeper') will be on hand to help you with anything you need.
Our user-friendly Pension Calculator can tell you whether you're on track to meet your retirement goal. Remember, consolidating your pensions isn't for everyone.
Is it ever better to leave my pensions where they are? What if there are exit fees or guaranteed benefits?
Some older pension types may contain valuable special benefits or exit fees. It's important that our customers are informed of significant exit fees that may have to be paid or special benefits that may be lost before transferring a pension. PensionBee doesn't provide financial advice and you'll need to find an Independent Financial Adviser (IFA) yourself. If you're advised against transferring to PensionBee in this scenario, we won't accept your transfer.
First, some background on special benefits and exit fees.
Special benefits (or "safeguarded benefits") can refer to a variety of different features, such as:
- Defined Benefits (sometimes known as final salary);
- Guaranteed Annuity Rates;
- Guaranteed Minimum Pensions; and
- Life Cover.
The most valuable of these include a guaranteed element of future pension income. You're required to obtain advice prior to transferring pensions with safeguarded benefits that have a total value over £30,000.
Exit fees can reduce the value of your pension. If we find a provider that has an exit fee of more than £10 we'll always seek our customers' permission to proceed with the transfer before taking action. It's important to note that, unfortunately, we can't guarantee we'll find an exit fee or special benefits as we rely on clear information from third parties. If the exit fee is below £10 we'll proceed with the transfer.
What type of provider is PensionBee?
PensionBee offers a defined contribution money purchase personal pension and allows the customer to select their own plan from a range of investments. Our money managers include BlackRock, HSBC and State Street. PensionBee doesn't provide financial advice or recommendations.
The PensionBee Personal Pension is governed by a Trust Deed and Rules. PensionBee Limited is the administrator of the scheme and PensionBee Trustees Limited are the trustees. You can find out more in our key literature, such as our Terms and Conditions and Key Features Document.
Can you explain the terms BeeHive, BeeKeeper and Nectar Collector?
The BeeHive is the customer's online account and is accessible via our website and app. BeeHive features include: live pension balance, easy bank transfer contributions, and more. A BeeKeeper is the customer's dedicated account manager. A Nectar Collector is the pension administrator.
Is PensionBee authorised and regulated by the Financial Conduct Authority?
Yes, PensionBee's authorised and regulated by the Financial Conduct Authority (FCA) (FRN: 744931). You can see this in the Financial Conduct Authority's register.
How much does it cost to use PensionBee?
We don't charge you any fees to transfer your pensions to PensionBee. There's just one single annual fee, which is calculated based on the daily value of your PensionBee plan. For pensions under £100,000 you'll pay one annual fee of 0.50 to 0.95%, depending on which plan you choose. If your pot size is larger than £100,000 we'll halve the fee on the portion of your savings over this amount. Use our Fee Calculator to see how much we reduce our fees with the more you save.
| PensionBee Plan | Annual management fee |
|---|---|
| Global Leaders Plan | 0.70% |
| 4Plus Plan | 0.85% |
| Climate Plan | 0.75% |
| Tracker Plan | 0.50% |
| Shariah Plan | 0.95% |
| Preserve Plan | 0.50% |
You can find more information on our Fees page.
Does PensionBee provide projections?
No, we don't provide bespoke projections. Instead we produce pre-sales and post-sales illustrations as well as Annual Statements. We have a pension calculator available in the 'Analytics' section of the BeeHive, but results from our calculators shouldn't be considered as an illustration.
Does PensionBee take clients with US tax/FATCA reporting requirements?
PensionBee's an active Non-Financial Foreign Entity as we don't hold client money. There's an agreement between the UK and the US that there is no reporting requirement for HMRC-registered pension schemes that are generally exempt from Income Tax and established to provide an income in retirement. The contracts with the investment managers are directly with PensionBee and not with the customers, therefore the investment managers also don't need to report on US end-clients.
Why can't I access the PensionBee app from the US?
Our app is only available in the UK App Store and Google Play Store at the moment. If you're in the US and have a UK account with us, you can access your PensionBee account (known as your 'BeeHive') on our UK website only. If you want to join PensionBee US, you can sign up via our US website.
What is Onfido?
You might be asked to complete a Facial Similarity Check (FSC) for a number of reasons. Most commonly, these requests are made during a change of personal details or your first withdrawal. To carry out a Facial Similarity Check, we've partnered with Onfido to provide you with a convenient and secure way to verify your identities.
Onfido uses its technology to verify your identity and will return the results to us. To complete a Facial Similarity Check, you'll need:
- a smartphone or tablet with a camera to take a selfie; and
- a valid form of photo identification, such as a passport or driving licence.
If the Facial Similarity Check doesn't pass, your BeeKeeper will review the results and invite you to try this verification method again as a first step. If you're still unable to digitally prove your identity, your BeeKeeper may need to request certified documents.
What customer information can PensionBee provide to regulated financial advisers?
PensionBee is set up to give information to financial advisors who are regulated by the FCA. We'll provide information only in response to a valid 'Letter of Authority'. As our systems are highly automated, we can't support an ongoing third-party from a compliance standpoint or guarantee that our level of service or communication will be the same.
If sending us a Letter of Authority (LOA), please make sure it includes:
- PensionBee Policy Number;
- full legal name;
- date of birth;
- registered address;
- National Insurance number; and
- customer's signature.*
*We accept electronic signatures.
We're looking into accommodating third parties, but we aren't set up to do this yet. We don't work with non-FCA regulated UK or overseas firms.
Does PensionBee support adviser charging?
No, PensionBee is an execution-only pension provider. We don't support adviser charging.
About signing up
How do I get started?
Simply download the PensionBee app or sign up online with some basic details, including your National Insurance (NI) number. If you're unable to locate it, you can easily find your NI number online using HMRC's free tool.
Joining us is free and we'll only start charging you one simple annual fee once we begin managing your pension.
You can pick from our diverse range of curated pension plans or we'll automatically invest you in one of our two default options depending on your age. Our Global Leaders Plan is our default for those under 50 with our 4Plus Plan the default option for those 50 or over. You can change your plan at any time by going to the 'Account' section of your BeeHive.
What if I don't have an email address?
In order to set up a PensionBee account, you need to have your own email address which you have full control over. We're a fully digital platform. We use two-factor authentication (2FA), also known as two-step authentication, which requires a mobile number and it's a feature we've built into your PensionBee account.
Can someone sign up on my behalf?
Yes, a person can sign up on behalf of a customer if they hold valid power of attorney or deputyship documents. However, they must provide certified copies of the court order documents, along with their ID and proof of address for our review.
Once we receive your documents, we'll review them to ensure they meet our requirements. If everything is in order, you'll be able to proceed with the sign up process. If there are any issues, we'll contact you for clarification.
Who's eligible to be a PensionBee customer?
Anyone with an existing UK pension can become a customer of PensionBee, regardless of nationality or tax residency. If you're self-employed, you can start a pension with PensionBee without needing an existing pension. People under 75 can get tax relief on pension contributions if they meet these requirements:
- you must have earned income in the UK that is taxable for that tax year;
- you must also be a resident of the UK at some point during that tax year; or
- you must have been a resident in the five years prior to that tax year and still be a resident when you join the scheme.
Alternatively, you can have earnings from overseas Crown employment that are subject to UK tax. Or be the spouse or civil partner of someone who has such earnings. Meeting these requirements makes you a 'relevant UK individual'. Only contributions from 'relevant UK individuals' are eligible for tax relief.
Customers are responsible for seeking their own tax advice, as eligibility and personal taxation affairs can vary significantly depending on individual circumstances, especially for those who are overseas or moving abroad.
From your retirement age (currently 55, and rising to 57 from 2028) you can access your pension money. Withdrawals must be paid into a UK bank account in the name and address of the customer (matching their PensionBee details). In addition, the bank must be directly regulated by the Prudential Regulation Authority (PRA). We're unable to authorise payments to any bank accounts that don't meet this criteria.
Do I have to provide any ID to open a PensionBee account?
Many pension providers, including PensionBee, use online processes to verify your identity. We don't usually require customers to provide ID, however if this is needed you can send it to us digitally. There are some providers who might require a certified copy of your ID, or name change document like a marriage certificate or deed poll.
In some cases, providers might ask you to send an original document in the post but we'll encourage them to accept a certified copy instead, to try to save you the hassle and to speed up the process. You can read our Acceptable Proof of Identification policy to learn more.
Are there rewards for referring friends to PensionBee?
Yes! We'll make a £100 contribution into your pension if you tell a friend about us and they open a PensionBee account with a pension balance of £100 or more.
About locating and transferring pensions
Do I have to transfer all of my pensions to PensionBee?
No, you only need to transfer one of your inactive pensions to PensionBee to get started. If your pension's still receiving contributions, you can add it to your online account (known as your 'BeeHive') and when payments stop you can transfer the pension over.
You can add as many pensions as you like, at any time in the future. And if you're self-employed, you don't need to transfer any pensions at all. Instead, you can start a new pension with us and contribute flexibly as much or as little as you like, as often as you like.
How do you transfer my pension?
When you sign up to PensionBee, we'll ask you questions about yourself and your pension in order to contact your old provider to begin the transfer process. This includes your:
- full legal name;
- email address;
- gender;
- date of birth;
- phone number;
- National Insurance number;
- current address;
- name of pension provider;
- if your pension is still receiving contributions; and
- your electronic signature.
You'll speed things up if you can provide us with information about your previous pension, such as your policy number.
How long does a transfer take?
On average, it takes 12 weeks to process and transfer your old pensions. PensionBee can only accept cash transfers. This means your investments with your old provider will be sold, the cash value will be transferred over to us, then we'll invest that sum into your new PensionBee plan. We don't accept 'in specie' transfers, where your existing investments are transferred from one provider to another.
We rely on your pension providers to give us information about your old pensions and some of them are quite slow. Occasionally providers will choose to send the transfer packet to you directly and instruct you to forward this information to us via post or as a scanned document. If you have your old paperwork, you can speed up the process by telling us your provider name, policy number and an estimated balance in your online account (known as your 'BeeHive').
Do I have to sign anything?
We believe that putting your pensions in one place should be straightforward and hassle-free. Therefore, when we gather information about your pensions, we'll only ask you to sign once digitally. As part of your sign up, you must confirm that you authorise us to use your signature digitally or physically by placing it on a standard letter of authority.
Most providers will accept a letter of authority with a digital signature, but if your provider insists on using paper with 'wet' signatures, we'll use our robot, Armie, to transpose your digital signature onto the letter with ink. We'll treat your signature as we treat all of your personal information in accordance with our Privacy Policy.
If your provider requires transfer forms, you'll need to sign these. Most customers can now sign these digitally, but very occasionally, we may need to post them out to you.
Can I transfer a defined benefit or public service pension?
Defined benefit pensions
If your old pension has guarantees, such as guaranteed annuity rates or a final salary promise worth over £30,000, we'll send you the full paperwork to review before we transfer it. If you have a pension with guaranteed benefits over £30,000, you're required to take financial advice from a FCA-regulated Independent Financial Adviser (IFA) before you transfer it.
Visit Unbiased to find an IFA or MoneyHelper for free guidance.
Where you're required to receive advice, PensionBee will only be able to accept the transfer if the advice is given or checked by a Pension Transfer Specialist. We'll require evidence of this positive advice before proceeding with the transfer. PensionBee doesn't provide financial advice and you'll need to find a Pension Transfer Specialist yourself.
Public service pensions
The government doesn't allow the transfer of unfunded government schemes, including those of the NHS, teachers, the army, police and firefighters. If you have a local government or civil service pension, you might be able to transfer a majority over to your PensionBee plan. For example, The Local Government Pension Scheme (LGPS) is a 'funded' arrangement so transfers from this scheme are still permitted. Please reach out to your personal account manager (your 'BeeKeeper') or the scheme provider.
What happens if I only have a pension that's being paid into by my employer?
If you only have one 'active' pension, that your employer's still paying into, you have a few options:
- ask your employer if they're happy to stop paying into your active pension and pay into your new PensionBee pension instead;
- PensionBee can attempt a partial transfer of your funds; or
- we can wait until you change jobs.
Most customers usually wait until they move jobs before transferring an active pension, to ensure they don't lose any special benefits from their current employer. But you can still add those non-PensionBee pots to your Retirement Planner and see the projected income you could expect from all of your retirement savings.
About the BeeHive
Why is my balance not updating in real-time?
At PensionBee your pension balance will reflect changes to the market two to three working days after they've occurred, rather than in real time, like in an Exchange Traded Fund (ETF).
This is because PensionBee uses insured index funds with the highest level of Financial Services Compensation Scheme (FSCS) protection should a money manager fail. We do this as many of our customers are moving away from workplace pensions (often structured as contracts of long-term insurance) to join PensionBee and we consider it important to offer the same type of insured funds that benefit from the 100% protection level.
These types of funds, for practical reasons, have their unit prices calculated retrospectively once a day and we use the latest available price from the money manager. They're distinctly different to other types of retail funds found with fund supermarkets, for example ETFs, which may update more regularly, often in real time, but don't offer the same level of FSCS protection.
Does PensionBee provide a list of all historic transactions?
Yes, this can be found under the 'Summary' tab of your online account (the 'BeeHive'). The 'Summary' tab logs both historic and pending transactions, including:
- contributions;
- financial rewards (such as our refer a friend scheme);
- HMRC tax relief;
- pension transfers; and
- withdrawals.
What's the current value of the plan the customer's invested in?
The customer is able to find this by accessing the 'Balance' section of their BeeHive. The 'fund value' and 'transfer fund value' are the same.
About contributions
How do I make contributions into my pension?
Contributing to your PensionBee pension is straightforward. Go to the 'Actions' tab and select 'Contribute' to get started. Then, select the type of contribution you want to make: personal, limited company, or employer contribution, and fill out a short online form. You can choose to make monthly or one-time contributions using Easy bank transfer or standing order. Contributing to your PensionBee pension is flexible and you can contribute as much or as little as you like, as often as you like.
You can make pension contributions from your personal, business, or joint bank account. However, with contributions from joint bank accounts your bank shouldn't require more than one signature for this. If it does, you can still contribute by setting up an Easy bank transfer. Please contact your dedicated account manager (known as your 'BeeKeeper') if you need more information.
It's free to make contributions into your pension and there are no minimum contribution amounts. Simply follow the instructions on-screen when making a contribution.
We don't offer a workplace pension scheme so we can't be used by businesses for Auto-Enrolment.
What is the maximum I can pay into my pension?
For the 2025/26 tax year, you can contribute up to the annual allowance of £60,000, which is the tax-free annual limit. This includes both contributions paid by you (with tax relief) and contributions paid by your employer. If you put more than this into your pension, you may pay a charge on any amount over the contribution limit.
Tax relief on individual contributions and contributions paid on your behalf by anybody other than your employer is limited to the higher of £3,600 gross a tax year or 100% of relevant UK earnings.
If you earn less than £3,600, or you don't earn anything at all, you're still allowed to receive tax relief on pension contributions up to £3,600 gross. That means you can save up to £2,880 net plus a 25% tax top up from HMRC.
There is a tapered allowance for higher and additional rate earners. It mainly affects people who earn over £200,000, and we've detailed the rates on our pension tax relief page. Your annual allowance may also be reduced if you have already flexibly accessed your pension.
What happens if you exceed the pension contribution limit
If you exceed the limit, you'll be eligible to pay tax on any amount over the contribution limit. This is called an 'annual allowance charge', and it'll be added to the rest of your taxable income for the year when your tax liability is calculated.
Alternatively, you may be able to ask your pension provider to pay the charge from your pension benefits. In some situations, you may be able to reduce the charge by bringing forward some of your unused annual allowance from previous years.
What's the carry forward rule?
If you use up all of your annual allowance in one year, it's possible to contribute more to your pension with unused allowances from previous years and still receive tax relief. You can carry forward unused annual allowances from the three previous tax years, starting with the earliest which would currently be 2022/23. Claiming tax relief on pension contributions for previous years is relatively straightforward as long as you were a member of a pension during that time.
One of the key pension annual allowance carry forward rules is that you can't receive tax relief on contributions in excess of your earnings in any tax year. For example if a person earns £80,000 in a tax year, they can only contribute up to £80,000 to their pension that tax year. No matter how much unused allowance they have remaining from the previous three years, they can only bring forward £20,000 so that their pension contributions equal their annual salary.
Are there any tax benefits to making pension contributions?
Pensions are a tax-efficient product for retirement saving. For the 2025/26 tax year, most eligible savers can get tax relief on individual pension contributions and contributions paid on your behalf by anybody other than your employer up to the higher of £3,600 gross a tax year or 100% of relevant UK earnings. This is limited by the annual allowance (£60,000 in 2025/26).
If you're making a personal contribution and you're eligible for tax relief, you'll receive a 25% tax top-up. For every £100 you put into your PensionBee pension, the government will add another £25 making it £125. We'll automatically claim your 25% tax top up and add it to your balance.
If you earn less than £3,600, or you don't earn anything at all, you're still allowed to receive tax relief on pension contributions up to £3,600 gross. That means you can save up to £2,880 net plus a 25% tax top up from HMRC.
PensionBee only accepts personal contributions that are eligible for tax relief. If you're a higher or additional rate taxpayer, you can usually claim back extra tax relief through Self-Assessment or by contacting HMRC directly.
How can I track my pension contributions and balance?
How long it takes to process your contribution differs, depending on whether you set up an Easy bank transfer or a standing order. Once money clears in our bank account, your contribution will show as a 'Personal contribution' in the 'Summary' tab in your online account (known as your 'BeeHive').
Easy bank transfer contributions
When using Easy bank transfer, your funds will typically arrive instantly though could take longer in some instances. It'll take up to five working days for our money managers to invest your funds into your pension.
Regular bank transfer contributions
Depending on your bank, setting up a regular bank transfer can take different amounts of time. Once the payment has left your account, it can take around eight working days for your funds to show as 'live' in your account. This includes the time taken for your funds to arrive in our account and be reconciled which is two to three working days, plus five working days for our money managers to invest your funds into your pension.
I'm self-employed, what kind of contribution should I make?
If you're a sole trader, you can only make a personal contribution. If you're the director of a limited company, you can make limited company contributions into your pension, as well as personal contributions, via your online account (known as your 'BeeHive').
If you're making a limited company contribution, the money needs to come from your business account. If you want to make a personal contribution, the payment needs to come from your personal account.
IR35 impact
IR35 is a complex bit of legislation that determines a contractor's tax liabilities. The amount of tax you need to pay on pension contributions doesn't change if you're inside IR35. The £60,000 annual pension allowance is unaffected. If you find that your take-home income decreases as a result of IR35, you may be able to minimise your tax liabilities by increasing your pension contributions.
Can I change or cancel my pension contributions?
To make changes or cancel your contribution, you'll need to edit your contribution in your own banking app. If you have a Direct Debit or Standing Order set up and would like to change it, it's likely you'll need to cancel it and start a new one. If you cancel your contribution, you'll also need to log into your online account (known as your 'BeeHive') afterwards to confirm you've cancelled it. Once a payment has been paid into your pension, it can't be refunded due to HMRC rules.
If you want to amend the amount or regularity of your contribution, you can do so without informing us.
Am I eligible for tax relief on my contributions?
To be eligible for tax relief, you must be under the age of 75 and classed as a 'relevant UK individual'.
To be a relevant UK individual, you'll need to be in at least one of the following categories:
- You are/were a UK resident for tax purposes at some point during the current tax year.
- You are/were a UK resident for tax purposes at some point during the last five tax years, and when signing up to PensionBee.
- You have a spouse/civil partner with general earnings from overseas Crown employment, subject to UK tax.
- You have 'relevant UK earnings'*, subject to income tax.
*Relevant UK earnings are normally your total taxable earnings from UK-based work. This includes earnings from employment, self-employment and bonuses. It generally doesn't include any investment income.
You're generally unable to claim tax relief on contributions above your relevant earnings. If you earn less than £3,600 annually or don't earn anything, the maximum amount you can contribute to your pension whilst receiving tax relief is £2,880 net, bringing your total annual contribution to £3,600 gross once tax relief is added.
What's the difference between a tax top up and tax relief?
If you're a registered tax payer, you won't have to pay tax on your pension contributions (up to a limit). This is known as tax relief.
The amount of tax relief you receive is dependent on the amount of income tax you pay. For most people, it's 20%.
This means that for every £100 you contribute to your pension, £20 of that is claimed back as tax relief. In effect, you only have to pay in £80 for every £100 that lands in your pension.
Here's another way to think of it... for every £80 you personally contribute to your pension, the government tops it up by £20. In effect, you receive a 25% tax top up.
So whether you view it as 20% tax relief or a 25% tax top up, the result is the same.
How do I claim back higher or additional rate tax relief?
Higher and additional rate taxpayers can claim a further 25% and 31% respectively through their Self-Assessment tax returns. This is relevant to tax rates in England, Wales and Northern Ireland. For Scotland there are different applicable rates which you can read more about on the HMRC website. It may be necessary to register for Self-Assessment first if you've never filled out a tax return before. Once registered, you can submit returns for the previous tax year from 6 April each year. For example, from 6 April 2026, you'll be able to file a tax return for your earnings from 6 April 2025 to 5 April 2026. The deadline to submit a return online is 31 January the following year. You can call or write to HMRC to claim it if you don't fill in a Self-Assessment tax return.
Can I claim tax relief if I'm not based in the UK?
Yes, as long as you're still classified as a 'relevant UK individual'*.
To be a relevant UK individual, you'll need to be in at least one of the following categories:
- You are/were a UK resident for tax purposes at some point during the current tax year.
- You are/were a UK resident for tax purposes at some point during the last five tax years, and when signing up to PensionBee.
- You have a spouse/civil partner with general earnings from overseas Crown employment, subject to UK tax.
- You have 'relevant UK earnings'**, subject to income tax.
*If you're not classified as a relevant UK individual, you won't be able to claim tax relief.
**Relevant UK earnings are normally your total taxable earnings from UK-based work. This includes earnings from employment, self-employment and bonuses. It generally doesn't include any investment income.
What is the difference between personal and business account contributions?
Most UK taxpayers get tax relief on pension contributions. If you're a basic rate taxpayer, when you pay a personal contribution into your pension you'll receive a 25% tax top up from HMRC. This means that for every £100 you contribute PensionBee will add another £25 from HMRC, making it £125. If you're a higher rate or additional rate taxpayer, you may be able to claim more tax back through your Self-Assessment.
If you'd like to calculate how much tax relief you could get on your pension contributions, use our Pension Tax Relief Calculator.
In contrast, if you choose to make an employer contribution through a limited company, it'll usually count as an allowable business expense.
Employer contributions aren't "topped up" by tax relief, but your contribution can be offset against your company's corporation tax bill.
Read an in-depth overview of the distinctions between personal and employer contributions.
About our plans and fees
What kind of pension plans does PensionBee offer?
We've carefully curated a range of diverse plans to meet a wide range of needs. So whether you're looking for a higher-risk or lower-risk plan, a plan that can help build a better world such as the Climate Plan or a specialist Shariah Plan, the choice is yours.
We're also committed to ensuring that our plans meet the changing expectations of our customers and regularly seek their views. If you don't want to choose one straight away, we'll automatically invest you in one of our two default options depending on your age. Our Global Leaders Plan is our default for those under 50 with our 4Plus Plan the default option for those 50 or over.
Remember, PensionBee's an execution-only service, which means we don't provide financial advice and can't advise you on which plan to pick.
| PensionBee Plan | Description |
|---|---|
| Global Leaders Plan | Aims to grow your pension savings by investing in approximately 1,000 of the world's largest and most recognised public companies. |
| Tracker Plan | Invests your money in global shares and bonds. Investments follow the world's markets as they move. |
| Climate Plan | Invests in companies actively reducing their carbon footprint over time. |
| 4Plus Plan | Aims to achieve long-term growth of 4% per year above the cash rate, by managing your money actively across a range of investments. |
| Preserve Plan | Makes short-term investments into creditworthy companies. This reduces risk and preserves your money. |
| Shariah Plan | Invests your money only into Shariah-compliant companies. Investments are approved by an independent Shariah committee. |
At PensionBee we only offer UK-based, FCA-regulated institutional life-wrapped funds (i.e. with the highest levels of governance). Most UK pensions have exposure to international markets, like the US, but that does not mean they are 'overseas' investments as per the definitions used by the DWP in the flag rules.
You can find more information on our Plans page.
Who manages the money in my PensionBee plan?
PensionBee allows you to select your own investment plan from a range of investments managed for you by one of our money managers (BlackRock for example). We've partnered with some of the world's biggest money managers to provide our investment choices, so no matter which of our pension plans you choose, you can rest assured that your money's in experienced hands.
| PensionBee Plan | Money manager |
|---|---|
| Global Leaders Plan | BlackRock |
| Tracker Plan | State Street |
| Climate Plan | State Street |
| 4Plus Plan | State Street |
| Shariah Plan | HSBC (traded via State Street Investment Management) |
| Preserve Plan | State Street |
You can find more information on our Plans page.
Where can I find plan information or ISINs?
Our plans are also available to view on Morningstar.
Tracker Plan
MPF Balanced Index Sub-Fund. ISIN: GB00BD35QM61.
Global Leaders Plan
BlackRock Life Global Equity Large Cap Screened Index Fund. ISIN: GB00BRTCSJ05.
4Plus Plan
MPF Dynamic Diversified Sub-Fund. ISIN: GB00BG217453.
Preserve Plan
MPF Stlg Liquidity Sub-Fund. ISIN: GB00BWDBJF10.
Climate Plan
State Street All World Climate Paris Aligned ex-Fossil Fuel Index Equity Sub-Fund. ISIN: GB00BGGK1F77.
Shariah Plan
HSBC MPF Islamic Equity Index Sub-Fund. ISIN: GB00BF2SYC67. (This fund is life-wrapped by State Street MPF).
What are the ISIN codes of all your plans?
Our plans are also available to view on Trustnet and Morningstar. We cannot guarantee the data accuracy of third party fund sites.
Tracker Plan
MPF Balanced Index Sub-Fund. ISIN: GB00BD35QM61.
Global Leaders Plan
BlackRock Life Global Equity Large Cap Screened Index Fund. ISIN: GB00BRTCSJ05.
4Plus Plan
MPF Dynamic Diversified Sub-Fund. ISIN: GB00BG217453.
Preserve Plan
MPF Stlg Liquidity Sub-Fund. ISIN: GB00BWDBJF10.
Climate Plan
State Street All World Climate Paris Aligned ex-Fossil Fuel Index Equity Sub-Fund. ISIN: GB00BGGK1F77.
Shariah Plan
HSBC MPF Islamic Equity Index Sub-Fund. ISIN: GB00BF2SYC67. (This fund is life-wrapped by State Street MPF).
How do I switch pension plans?
When you have a live PensionBee balance, either from making a contribution or transferring your first pension over, we'll automatically invest your funds depending on your age (unless you sign up from a plan specific page, for example, the Climate Plan):
- under 50s will be invested in our Global Leaders Plan designed for the 'accumulation' (or growth) years; and
- over 50s will be invested in our 4Plus Plan designed for the 'decumulation' (or withdrawal) years.
Once your online account (known as your 'BeeHive') set up is complete, you'll be able to immediately switch to a different plan by going to 'My Pension' and 'Switch plan'. If your pension transfer's already been completed, you'll be able to switch plans at any time from here too.
Does PensionBee charge a fee to change my plan?
No, we don't charge any fees to change your plan but there may be small transaction costs associated with switching, to protect other investors in the fund. These are charged by money managers and PensionBee doesn't make any money from them.
How long does switching plans take?
This process can take up to 12 working days. A plan switch involves the disinvestment and reinvestment of cash, with funds being out of markets for a short period of time. Plan switches are a business-as-usual activity for our money managers.
Why has my balance changed after switching plans?
Whilst your switch takes place your investment is sold to cash and your balance is frozen. However, the market can still move up or down during this time, meaning when funds are reinvested they could be worth more or less than when they were sold. This will be reflected in your new balance once the switch has completed. It's not possible to time switches or predict market movement.
Are there any costs involved with switching plans?
It's standard industry practice that plan switches have small transaction costs associated with them, both at PensionBee and all other pension providers. PensionBee doesn't make any money from these switching costs.
These costs, also known as an 'anti-dilution levy', are designed to protect existing investors from switching activity into or out of their fund. The subscription (when you buy units) and redemption (when you sell units) fund spreads are based on market conditions on the day of the switch.
These costs are an unavoidable feature of the market when moving money between different funds and there to ensure existing investors are not negatively impacted by the switching activity of others.
Are customers able to switch plans?
Yes, customers can switch between plans online under the 'Plans' section of their BeeHive.
Is there a limit on the number of plan switches per year?
No, there is no limit to the number of plan switches a customer can make.
What investment options are available to customers?
Customers can only invest in one plan (or fund) at a time, as we don't offer plan splitting. All our plans are unit linked and each plan is managed by either:
- BlackRock;
- HSBC; or
- State Street.
We've carefully selected a range of plans to meet various savings needs and customers can choose one of our plans to invest in. We offer diversified plans, meaning they invest across different countries and asset types (such as company shares and bonds). At PensionBee, one of our core values is simplicity so we do not currently offer customers the ability to invest in more than one plan at a time.
Please visit our Plans page for a full summary of all the options available.
Do your plans have multiple sections?
No, our plans don't have multiple sections.
Are these funds illiquid or liquid?
All our investment plans are liquid.
What's the Allocation Rate on PensionBee pensions?
The Allocation Rate on our pensions is 100%.
Do you charge any extra fees?
At PensionBee, we take care of customers' pensions for one simple annual fee. You can find more information on our Fees page.
Are there any fees associated with a customer making contributions?
No, it's free for customers to make contributions.
Do you charge an initial setup fee?
No, there is no initial setup fee.
Is there a fee for switching plans?
No, PensionBee doesn't charge for plan switches.
Where can I find a fund breakdown?
All relevant information can be found via our plans page.
What are the annual costs?
Annual costs vary by investment choice. Please see our Fees page for a full summary. Please note the quoted annual management costs include both fund and wrapper charges.
What are the transaction costs?
Our transaction costs disclosure for plans can be found on our website.
Are there any fee waivers or discounts?
There are no fee waivers. There is a fee discount: we'll halve the fee on the part of savings over £100,000. Fee rebates or reinvestment of charges are not applicable to PensionBee.
What special benefits do you offer?
We don't offer any special benefits with our defined contribution pension plans.
Do any of your plans have bonuses attached?
No, none of our plans have bonuses attached. We don't offer any with-profits plans or protected tax-free cash.
Do any of your plans have life cover or accidental death cover attached?
No, our plans don't have life cover or accidental death cover attached. We've never offered these types of plans in the past.
Do any of your plans have guaranteed annuity rates or other guarantees attached?
No, none of our plans have guarantees attached to them.
Do any of your plans have a protected pension age?
No, none of our plans have a protected pension age.
Is bid offer spread applicable?
PensionBee plans do not have a bid offer spread. All our funds are forward priced funds, using swing pricing. Swing pricing is an anti-dilution mechanism which protects fund shareholders by countering the dilution effect of subscription and redemption activity. This means all buy and sell orders on the same day have the same unit price.
What's the pension input period?
The pension input period runs in line with the tax year.
About living overseas
What will happen to my PensionBee pension if I move abroad?
You now have the choice of what you'd like to do with your pension if you move abroad.
This means you can choose to leave your pension where it is, and you can even continue to pay into your UK pension plan. There may be a limit to the amount of tax relief you can claim though, so you should look into this more if you're thinking of continuing payments.
Alternatively, you may be able to transfer your pension to a Recognised Overseas Pension Scheme (ROPS). Get in touch with your BeeKeeper if you wish to request the transfer so that we can confirm initial requirements. Please be aware, we review each request on a case-by-case basis and there are extensive checks required under HMRC's transfer regulation rules.
Can I contribute to my PensionBee pension if I'm not based in the UK?
As long as you're still classified as a 'relevant UK individual', you can keep paying into your PensionBee pension. If you're not classified as a relevant UK individual, you won't be able to contribute. To be a relevant UK individual, you'll need to be in at least one of the following categories:
- you're/were a UK resident for tax purposes at some point during the current tax year;
- you're/were a UK resident for tax purposes at some point during the last five tax years, and when signing up to PensionBee;
- you've a spouse/civil partner with general earnings from overseas Crown employment, subject to UK tax; or
- you have 'relevant UK earnings'*, subject to Income Tax.
If you're unsure, speak to a specialist tax advisor to better understand your situation.
*Relevant UK earnings are normally your total taxable earnings from UK-based work. This includes earnings from employment, self-employment and bonuses. It generally doesn't include any investment income.
Can I withdraw from my PensionBee pension if I'm not based in the UK?
Withdrawals must be paid into a UK bank account in the name and address of the customer (matching their PensionBee details). In addition, the bank must be directly regulated by the Prudential Regulation Authority (PRA). We're unable to authorise payments to any bank accounts that don't meet this criteria. If you don't hold a UK bank account that meets these criteria, then you can't make any withdrawals from your PensionBee pension and you'll need to transfer to another FCA-regulated, UK-based pension scheme in order to access it.
Can I transfer an international pension to PensionBee?
No, unfortunately we can't transfer a pension from outside the UK into your PensionBee plan. This restriction includes pensions from the Isle of Man, Jersey, the Channel Islands, and the Republic of Ireland.
I don't currently have a UK address, what do I do?
It's OK if you don't have a UK address at the moment, but you'll need to tell us your previous UK address when you sign up. Please be aware that we use emails wherever possible and don't send our customers letters unless we really have to (e.g. your old provider demands a physical copy of your signature on one of our letters).
After you've signed up, you can request that we update your address by calling us on 020 3457 8444, and we can amend this using a bank statement or utility bill. It must be:
- from the country that you now reside in;
- translated into English, if originally in another language; and
- dated within the last three months.
Please note: we won't be able to register you with an overseas address until you've left the UK.
About withdrawals
How do I withdraw money from my pension?
Accessing your pension is straightforward and our app allows you to withdraw with ease when you reach 55 (rising to 57 from 2028). You can take up to 25% as a tax-free lump sum (or multiple lump sums), and leave the rest invested. Once you become eligible, our drawdown option gets activated automatically.
Before withdrawing money from your pension, we'll ask you to confirm that you're happy to go ahead with the withdrawal and have considered taking advice. You might be asked to complete a Facial Similarity Check (FSC) for a number of reasons. These requests are always made during your first withdrawal request.
To carry out a Facial Similarity Check, we've partnered with Onfido to provide our customers with a convenient and secure way to verify their identities. You'll need to have a smartphone or tablet with a camera to take a selfie. Plus you'll need to upload a copy of one of the following:
- passport;
- driver's licence, or provisional driver's licence; or
- national identity card.
Does it cost to withdraw money?
Unlike other providers we won't charge you extra fees for drawing down your pension. However, if your pot has been with PensionBee for less than a year and you wish to withdraw it in full, then a full withdrawal fee of £150 applies. Including if the value of your account's less than £150 at the point of withdrawal.
What type of account am I able to withdraw money into?
You can make one taxable cash withdrawal per tax month. Withdrawals must be paid into a UK bank account in the name and address of the customer (matching their PensionBee details). In addition, the bank must be directly regulated by the Prudential Regulation Authority (PRA). We're unable to authorise payments to any bank accounts that don't meet this criteria.
When can customers withdraw money from their pension?
Based on current legislation, customers can access their pension from the age of 55 (this will rise to the age of 57 on 6 April 2028). We don't offer customers any protected retirement age benefits with their pension. Once customers become eligible, our drawdown options get activated automatically. There's no maximum age for customers to withdraw funds or their available tax-free cash.
What is the customer's retirement date?
We assume a retirement age of 65 for all customers.
What if a customer dies?
On the death of a customer, we only support lump sum death benefits payments. Customers are able to add their preferred beneficiaries through their BeeHive.
How can customers withdraw money from their pension?
Customers can make one taxable cash withdrawal per tax month. Withdrawals must be paid into a UK bank account in the name and address of the customer (matching their PensionBee details). In addition, the bank must be directly regulated by the Prudential Regulation Authority (PRA). We're unable to authorise payments to any bank accounts that don't meet this criteria.
Can a regular monthly income be set up?
Yes, with Automatic withdrawals, you can set up automatic monthly payments. Choose the amount and the date, and your money will land in your bank account each month without repeated steps. This is currently available in the Android app and website and will soon be available to iOS users.
Do customers need to move this existing plan to go into drawdown?
No, internal transfers aren't required for drawdown.
What funds are available to customers once they're in drawdown?
Our plans are available to all customers, regardless of drawdown status. These can be found on our Plans page.
Does it cost anything to withdraw money?
Unlike other providers, we won't charge customers extra fees for pension drawdown. If a customer's pot has been with PensionBee for less than a year and they withdraw it in full, a full withdrawal fee of £150 will apply. This is issued, even if the value of their account is less than £150, at the point of withdrawal.
Are there any ad-hoc withdrawal fees?
No, there are no ad-hoc withdrawal fees for drawdown.
Is there a minimum withdrawal amount?
No, there's no minimum withdrawal amount for drawdown.
Does the annual management charge change when the customer is in drawdown?
No, the annual management charge doesn't change at drawdown.
How can I track my pension withdrawals and balance?
If withdrawal requests are made before 12pm on a working day, we'll aim to make a trade request on that particular day. Requests made after 12pm may be processed the following working day. As long as there are no issues verifying your bank details, it should take around 10 working days for you to receive your money.
There are no forms to sign as everything is done digitally, including your emergency tax payment to HMRC. Once the payment has cleared, your withdrawal will show as a 'Withdrawal' in the 'Summary' tab in your online account (known as your 'BeeHive').
What are the tax implications of drawdown?
You can take up to 25% of your pension pot tax-free, either as a lump sum or as a portion of each withdrawal. The remaining 75% of your pension pot is subject to Income Tax. When you withdraw a taxable lump-sum from your pension, an emergency tax rate will be charged until your individual tax code is received from HMRC directly.
As pension tax works in the same way as Income Tax, your pension provider will use the Pay As You Earn (PAYE) system to deduct any tax due before you receive your payment. For payments processed using an emergency tax code, under PAYE, any payments you receive will be treated as though they're a regular salary or monthly income.
It's important to understand how this impacts your pension plan. You can use our Pension Drawdown Calculator to estimate how much tax you'll pay and how much you'll have left in your pension pot. MoneyHelper and Pension Wise offer free impartial financial guidance. They can help you understand your options and make the best decision for your individual circumstances.
How can I get back emergency tax?
You may be able to reclaim emergency tax on your withdrawals by contacting HMRC directly, and completing a tax claim form. Please keep the payslip we issue when you make a withdrawal in a safe place, and refer to it when contacting HMRC.
Can I drawdown part of my 25% tax-free cash now, and some at a later date?
Yes, for customers over the age of 55 (expected to rise to 57 in 2028), PensionBee offers the ability to be completely flexible with your drawdown. It's important to consider the pension "recycling rules" if you intend on making pension contributions following a withdrawal. Pension recycling is where an individual reinvests either their tax-free cash or pension income back into a pension scheme and may be subject to tax penalties.
Are there any special benefits available to drawdown customers?
When customers reach the age of 55 (rising to 57 in 2028) we give them two ways to withdraw money from their pension:
- take their pension through PensionBee's flexi-access drawdown; and / or
- buy a pension annuity through our partner, Legal & General.
Are the small pot options available when encashing?
No, this feature isn't available.
Can you take more than 25% protected tax-free cash?
No, we don't offer more than 25% protected tax-free cash.
Does PensionBee offer the uncrystallised fund lump sum option?
No, we only offer flexi-access drawdown.
What are pension annuities?
A pension annuity's a financial product that pays you a guaranteed income for a fixed period or for the rest of your life. When you retire, you can choose to use some or all of your pension savings to buy an annuity.
We have a partnership with Legal & General to enable PensionBee customers to use their pension balance with us to purchase a pension annuity via Legal & General. Just go to our Pension Annuity landing page to find out more.
We do earn a referral fee of 1.25% of the total money used to purchase a pension annuity from Legal & General, however this doesn't impact the annuity you'll receive.
Does PensionBee offer a Protected Pension Age?
Protected Pension Age (PPA) applies on a scheme-by-scheme basis. The scheme rules governing the PensionBee pension confirm that the age customers can start to take benefits is in line with the Normal Minimum Pension Age (NMPA). This means PensionBee doesn't offer PPA on our scheme. PensionBee allows withdrawals from the NMPA of 55 (rising to 57 from 2028).
However, if you transfer a pension to PensionBee from a provider that offers PPA of 55 or 56, we'll honour this, where we've correctly been informed. We'll administer this in due course, so that you may be able to access a proportion of your pension once you reach the relevant age.
While your PPA will give you the right to access these funds early, we recommend customers think very carefully before doing so. Taking benefits earlier will result in a smaller overall pot and less time for investments to potentially grow, which could impact standard of living later in retirement.
For free, impartial guidance on your options, we strongly encourage you to visit MoneyHelper.
How do I nominate beneficiaries for my pension?
Pensions aren't considered to be part of your estate, which means that pension death benefits are typically free of Inheritance Tax (IHT). Some conditions will apply depending on how old you are when you die and the type of pension you have in place. You can set up your PensionBee beneficiaries in your online account (known as your 'BeeHive').
For defined contribution pensions:
- if you die before age 75, your beneficiaries have two years to claim your entire pot tax-free;
- if you die before age 75, it's possible for your beneficiaries to access your pot as a tax-free lump sum or sometimes to receive regular drawdown payments tax-free; or
- if you're older than 75 when you die, your beneficiaries will have to pay Income Tax at their usual rate to receive your defined contribution pension. This is also the case if funds are paid out or designated to drawdown after two years have passed.
PensionBee is a defined contribution pension scheme. We only offer accepted beneficiaries the option of taking the inherited pot as a lump sum payment.
For defined benefit pensions:
- if you die before age 75, and haven't touched your pension, your beneficiaries will usually receive a tax-free lump sum. Your pension may pay out a lump sum worth two to four times your salary. Check with your scheme administrator for more details.
- if you're older than 75 when you die, it's likely that your spouse, civil partner or dependant will receive a portion of your pension, however this may be subject to tax charges.
You can change your nominated beneficiaries at any time, which is particularly important if your circumstances change. While PensionBee isn't bound by your request, it's important to make a nomination and keep it up to date so that your wishes are known. You can read more about what happens in the Key Features Document.
What happens when a PensionBee customer dies?
We understand that dealing with the death of a loved one is a difficult time, so we try to make notification as easy as possible.
To notify PensionBee that one of our customers has passed away, please call 020 3457 8444 or email us at contact@pensionbee.com.
You'll need to have the personal details of our customer to hand so that we can locate their account. These details may include their:
- full legal name;
- date of birth; and
- registered address.
We'll send a form by email which needs to be completed and returned by the individual handling our customer's financial affairs. For example:
- the Executor;
- Administrator; or
- closest next of kin.
The form will ask you to upload certain key documents such as:
- Final Death Certificate; and (if applicable)
- the Will;
- Letter of Administration; and/or
- Marriage Certificate.
Once received, one of our Compliance Managers will review the information. We'll then be in contact to confirm anything else we may need and explain the next steps.
If you need any information relating to handling the affairs of a loved one in general, there are a range of death and bereavement guides on the MoneyHelper website which can be accessed, free of charge.
How do I notify you if a PensionBee customer has passed away?
We understand that losing a loved one is a challenging time, so each claim will be handled by a specialist Compliance Manager at PensionBee. To notify PensionBee about the passing of a customer, the next of kin or executor of the estate should get in touch with us. If they need to notify us, they can call us as a first step. If they're unable to call, they can send us an email.
For security reasons and to locate the customer's account, they'll need to provide the following:
- full legal name;
- date of birth;
- National Insurance number; and
- current address.
Once we receive this information, we'll update our records to reflect the bereavement. We'll also send a form that needs to be filled out and returned to us.
To begin the review of any death benefits that may be payable from the customer's plan, the form must be completed in full and returned along with the final death certificate and any other relevant supporting documents. The Compliance Manager will confirm any further requirements upon return of the form and provide guidance on next steps.
We can't provide a definite time frame for the completion of our review, approval of beneficiaries and associated payments. This is because the process involves multiple parties and we rely on third parties for certain aspects of it. The final decision regarding who any death benefits will be paid to lies with us as scheme administrator and trustee.
Can I transfer a pension already in drawdown?
While the answer's generally yes, there are a few things you need to be aware of before making the decision to transfer a pension in drawdown.
If your current pension's in Capped Drawdown, it'll be converted to Flexi-Access Drawdown. Flexibly accessing your pension after converting would result in you becoming subject to the Money Purchase Annual Allowance (MPAA).
Also you must transfer the entire value of a pot in drawdown because HMRC doesn't allow splitting crystallised funds.
If your current drawdown product is giving you a regular monthly income, please note that this isn't a feature we accommodate at the moment, you'll need to make a new request each time you want to draw down part of your pension.
Please note, we can't currently accept beneficiaries drawdown from other providers. If a customer passes away whilst with us, the accepted beneficiaries will receive the inherited pension as a lump sum death benefit.
About transferring out of PensionBee
Is there an exit fee to leave PensionBee?
There's no exit fee if you leave PensionBee at any point. There's also a 30 day cancellation policy, which means we'll return your pensions to your old providers (assuming they're also willing to take them back), free of charge if you cancel your PensionBee plan within 30 days of opening it. You can find more information on our Fees page.
If your provider is using Origo Options, they'll need to request a transfer through the electronic system. Please ask them to search for PensionBee in order to avoid delays.
If your provider isn't using Origo Options, they'll need to email their completed transfer-in forms to transfersout@pensionbee.com.
If these forms aren't complete, it's likely we'll require further information to initiate a transfer.
We'll send you a confirmation email to let you know when we've received your new provider's completed forms. PensionBee can only transfer out to UK based, HMRC registered pension schemes. If you're planning on moving abroad, and taking your pension with you, please read our article, Overseas pension transfers, for more information.
Do we charge any early exit or transfer out fees?
There is no exit fee if a customer leaves PensionBee at any point. There's also a 30-day cancellation policy. This means we'll return a customer's pensions to their old providers free of charge if they cancel within 30 days. Please note, this assumes the old provider is willing to take back their funds. You can find more information on our Fees page.
How long does it take to transfer my pension out of PensionBee?
The transfer out process begins when your new provider sends us all of the required information to complete your transfer out. We'll send you a confirmation email too. From this point, PensionBee aims to transfer to most other Financial Conduct Authority (FCA) regulated personal pension companies on Origo Options within 14 days. The majority of the industry has subscribed to this electronic transfer service.
Due to the threat of pension scams, which include fraudulent companies and also pension liberators who promise to release monies in your pension before the age of 55 (rising to 57 from 2028) while avoiding heavy tax charges, other transfers may take longer and we're required by the regulators to perform additional due diligence checks.
This process may be dependent on obtaining important information from third parties (such as HMRC). Whilst this could take up to six months (the legal deadline for pension transfers) we'll endeavour to complete this as soon as possible. It's important for us to complete our diligence, as otherwise, you and we may be subject to onerous tax charges from HMRC. We may decline a transfer out to meet our regulatory obligations.
What is PensionBee's transfer out process?
If a customer's new provider uses Origo Options, they'll need to request a transfer that way. They should search for 'PensionBee' to avoid delays. PensionBee aims to transfer to other eligible schemes within 14 days. Eligible pension schemes are Financial Conduct Authority regulated and The Pensions Regulator authorised.
If the provider isn't using Origo Options, they'll need to email us the transfer request which should include full receiving scheme details and their own transfer application forms signed by the customer. The contact email is transfersout@pensionbee.com.
We'll need to request further information if any details are missing. Our average transfer out time to other UK regulated providers is 10 days.
If sending us a Letter of Authority (LOA), please make sure it includes the following:
- PensionBee Policy Number;
- full legal name;
- date of birth;
- registered address;
- National Insurance number; and
- customer's signature.*
*We accept electronic signatures.
The process of transferring a pension may take up to six months, as we may need to get information from third parties, such as HMRC. We'll endeavour to complete this as soon as possible. We won't usually need identification, though in some cases this may be required. We may decline a transfer out in order to meet our regulatory obligations.
Does PensionBee allow partial transfers out?
Yes, we do. Partial transfers are permitted, but 5% needs to be left in the pot. These should be requested by the receiving provider on Origo Options. There's no minimum value that can be transferred out of the plan.
Is PensionBee part of a block or bulk transfer?
No, PensionBee transfers pensions on an individual basis and this isn't part of a bulk or block transfer.
Are any of your plans suspended or closed for customers looking to transfer out?
All our plans are liquid. We don't currently have a property fund.
Can I change my mind about any (or all) of my pensions?
Yes. You can choose to cancel any individual pensions that haven't started transferring in the BeeHive. We'll send your pension back to your provider for up to 30 days after the transfer, as long as they agree to accept it. If you'd like to close your account overall, please email your dedicated account manager (known as your 'BeeKeeper'). You can also transfer your PensionBee pension to a new provider and we won't charge you an exit fee.
About PensionBee security and data protection
Is my pension protected by the Financial Services Compensation Scheme?
Yes. A typical PensionBee customer will be invested in the PensionBee Personal Pension. Our money managers will keep these assets safe using global custodians. This includes:
- Bank of New York Mellon (BlackRock); and
- State Street Bank (State Street).
The holdings in the PensionBee Personal Pension are structured as long-term insurance contracts. If our money managers collapse, we'll contact the Financial Services Compensation Scheme (FSCS). If they accept our claim, they'll cover 100% of the pension, with no upper cap. PensionBee will pursue compensation on your behalf.
Information on the FSCS applicability to pensions and to PensionBee is available here.
Are PensionBee pensions protected by the Financial Services Compensation Scheme (FSCS)?
Yes, a typical PensionBee customer will be invested in the PensionBee Personal Pension. Our money managers will keep these assets safe using global custodians, including:
- Bank of New York Mellon (BlackRock);
- State Street Bank (State Street Investment Management); and
- Citibank (Legal & General Investment Management).
The holdings in the PensionBee Personal Pension are structured as long-term insurance contracts. If our money managers collapse, we'll contact the Financial Services Compensation Scheme (FSCS). If they accept our claim, they'll cover 100% of the pension, with no upper cap. PensionBee will pursue compensation on behalf of our customers.
Information on the FSCS applicability to pensions and to PensionBee is available here.
How do you protect my personal information?
At PensionBee, we take the security of your personal information very seriously. We take various administrative, legal, technical and physical precautions. This ensures the security of your information, all in line with the Data Protection Act 2018 and the UK General Data Protection Regulation ('UK GDPR'). By entering your information into our system, you give us permission to use your information in line with our Privacy Policy.
How do you protect customer information?
At PensionBee, we take the security of our customers' personal information very seriously. We take administrative, legal, technical and physical precautions to ensure the security of customer information, all in accordance with the Data Protection Act 2018 and the UK General Data Protection Regulation ('UK GDPR').
By entering their information into our system, our customers give us permission to use their information in accordance with our Privacy Policy.
What are the digital security policies of PensionBee?
All communications between your browser and our website are secured using 128-bit TLS encryption, to ensure that only people authorised to view your personal information can do so. Information is stored in secure databases and data centres accredited to multiple internationally recognised standards. Our security controls are tested on an annual basis by independent experts.