


Behind the pension pot: Joumana on saving for retirement as a freelancer


When Joumana, 46, moved to the UK from Lebanon 13 years ago, opening a personal pension wasn't something she'd considered. It wasn't that she’d decided to put retirement saving off. She simply didn't know it was an option.
Now based in Oxford, Joumana works as a freelance Artist and Independent Researcher. Her income can be unpredictable, and growing up in a country where financial security was far from guaranteed has shaped how she thinks about saving for the future.
Money wasn't a subject people discussed openly when she was growing up, either.
"Discussing money is a taboo subject in Lebanon. It's just not done. You don't talk about it. It's considered to be indecent."
It wasn't until she turned 45 that she opened her first personal pension. By then, she'd spent more than a decade living in Britain without fully understanding how the UK pension system worked or what she could do to prepare for retirement.
She's since taken steps to understand her State Pension, made voluntary National Insurance (NI) contributions and started saving into a personal pension when her freelance income allows.
Looking back, her biggest regret isn't that she didn't save more. It's that nobody explained her options sooner.
Learning about pensions came later in life
When Joumana arrived in Britain, she knew very little about personal pensions. Growing up in Lebanon, where she describes the financial system as unreliable and difficult to navigate, she had no reason to assume that opening a pension was something she should be thinking about.
Unlike employees who may be introduced to workplace pensions through Auto-Enrolment, Joumana was working for herself. That meant learning about pensions and arranging her own savings without the same support.
"I didn't even know it was a possibility to open a personal pension, and that it was a good idea, and that the State Pension would probably not be enough. I had no idea."
She wishes there had been a simple guide to help people arriving in the UK understand how the financial system works, from everyday banking to saving for retirement.
"I would've loved to have started saving for my pension when I arrived, even if it was tiny sums at first."
For Joumana, the delay wasn't about avoiding a difficult financial decision. It was about not knowing there was a decision to make in the first place.
{{main-cta}}
Making up for missing years
Opening a personal pension was only one part of Joumana's journey. After moving to the UK as an adult, she also started looking into her NI record and what it could mean for her future State Pension.
She discovered that she had missing years and was given the option to make voluntary contributions to fill some of those gaps. But the cost was significant, particularly when she had other financial priorities to consider.
"At one point I had an option to buy some NI years that were missing. And it was quite a big sum for me to pay at the time and I was wondering: 'Is it worth it? Is it not worth it?'"
After weighing up the cost and the possible benefit, she decided to pay for the missing years. She wasn't expecting it to transform her retirement income, but felt it could make a difference.
Her experience shows how pension planning can involve looking backwards as well as forwards. Before deciding how much to save, it can help to understand what you're already entitled to and whether there are gaps in your record.
Good to know: Your State Pension is based on your NI record. You'll usually need at least 10 qualifying years to receive any new State Pension, and typically 35 years for the full amount, although this can vary. You can check your State Pension forecast and NI record for free on GOV.UK.
Freelance income doesn't follow a plan
As a freelance artist, Joumana knows how unpredictable work can be.
"So because I'm a freelance artist, the work is a bit [of a] feast or famine. So you have very good years, and then you have years where there's nothing."
Like many self-employed workers, she has no employer contributing to her pension, making it harder to save consistently.
Joumana paid more into her pension when she could afford to, but has paused contributions while work is quieter. She's also chosen a plan with a level of investment risk she's comfortable with.
Good to know: With PensionBee, you can make regular or one-off pension contributions and pause payments when needed. Your existing pension savings remain invested when you stop contributing, although their value can go down as well as up. If you're self-employed, it's also worth understanding the pension contribution limits and tax relief rules that apply to you.
Why Joumana doesn't put all her eggs in one basket
Joumana's approach to saving has also been shaped by events in Lebanon. The country's financial crisis, which began in 2019, left many people unable to access savings held in their bank accounts.
Having witnessed that uncertainty, she finds it difficult to assume that any financial arrangement will always work as expected.
"I've just seen it in my own country a few years ago where everybody's bank accounts vanished overnight. They're gone. Everything's gone. All the savings - zero. Nobody has anything left."
It's an experience that helps explain why she's cautious about putting too much of her income into any single place, including her pension.
While she wants to build savings for later life, she doesn't want to do so at the expense of enjoying the years leading up to retirement.
"I don't put all my eggs in the same basket. This is why I don't contribute lots to my pension and live meagrely - because I could arrive there and then it's not there, and then I've wasted my life not living."
Good to know: Your PensionBee pension’s structured as a long-term insurance contract. The money in it is managed by some of the world’s largest money managers, such as BlackRock and State Street. If something happens to the money managers and the FSCS accepts the claim, they would cover up to 100% of your pension, with no upper cap.
Because PensionBee has arranged the contracts with the money managers, we’ll pursue the compensation on your behalf.
Retirement doesn't mean giving up work
Joumana and her partner have started discussing retirement, although they approach planning differently. When he recently asked where they should buy a house for retirement, she struggled to answer.
"I come from a place of massive uncertainty, and I don't know what's going to happen one year to the next."
But Joumana knows what she wants from retirement. She hopes to keep working as an artist, without the financial pressure of having to earn a living.
"I don't imagine retiring in the sense of stopping to do my job. But I’d really love a house that is paid for, and knowing I can always pay my bills, and I can just continue doing my work without worrying."
Ultimately, her goal is less about stopping work and more about financial security.
Peace from insecurity. That's basically all I'm after.
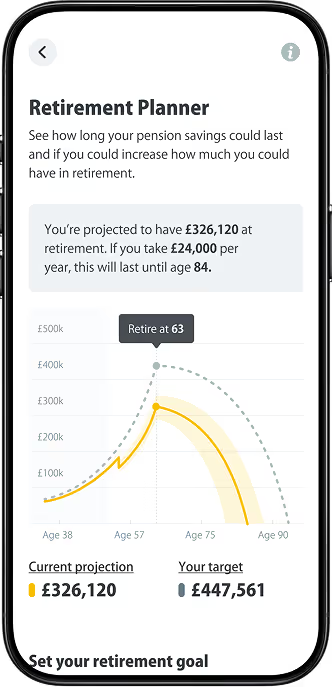
Good to know: Retirement planning can start with thinking about the life you'd like to lead, rather than aiming for a particular savings figure. Pensions UK's Retirement Living Standards offer examples of what different retirement lifestyles might cost, while PensionBee's Pension Calculator can help you explore how your savings and contributions could support your plans. These are guides, not guarantees of what you'll need.
The takeaway
Joumana's pension journey started later than she'd have liked, but her experience shows how much someone's background and circumstances can shape their relationship with money.
Moving to a new country meant learning an unfamiliar pension system, while the ups and downs of freelance work made regular saving difficult. Her experience of financial uncertainty in Lebanon has also made her cautious about relying too heavily on any single plan.
Now, at 46, she's opened a personal pension, filled gaps in her NI record and found a way to approach saving that reflects her circumstances.
For Joumana, a happy retirement means having peace of mind about money and the freedom to enjoy life. And while retirement may still be some way off, every step she takes towards feeling more financially secure can help make that future feel a little closer.
Risk warning
As always with investments, your capital is at risk. The value of your investment can go down as well as up, and you may get back less than you invest. This information shouldn't be regarded as financial advice.
Period | Market Event | FTSE World TR GBP (%) | 4Plus Plan (%) |
|---|---|---|---|
4Plus Plan’s inception – 6 Sept 2013 | QE Tapering, China Interbank Crisis and its aftermath | -5.44 | -2.41 |
3 Oct 2014 – 15 May 2015 | Oil price drop, Eurozone deflation fears & Greek election outcome | -5.87 | -1.77 |
7 Jan 2016 – 14 Mar 2016 | China’s currency policy turmoil, collapse in oil prices and weak US activity | -7.26 | -1.54 |
15 June 2016 – 30 June 2016 | BREXIT referendum | -2.05 | -1.07 |