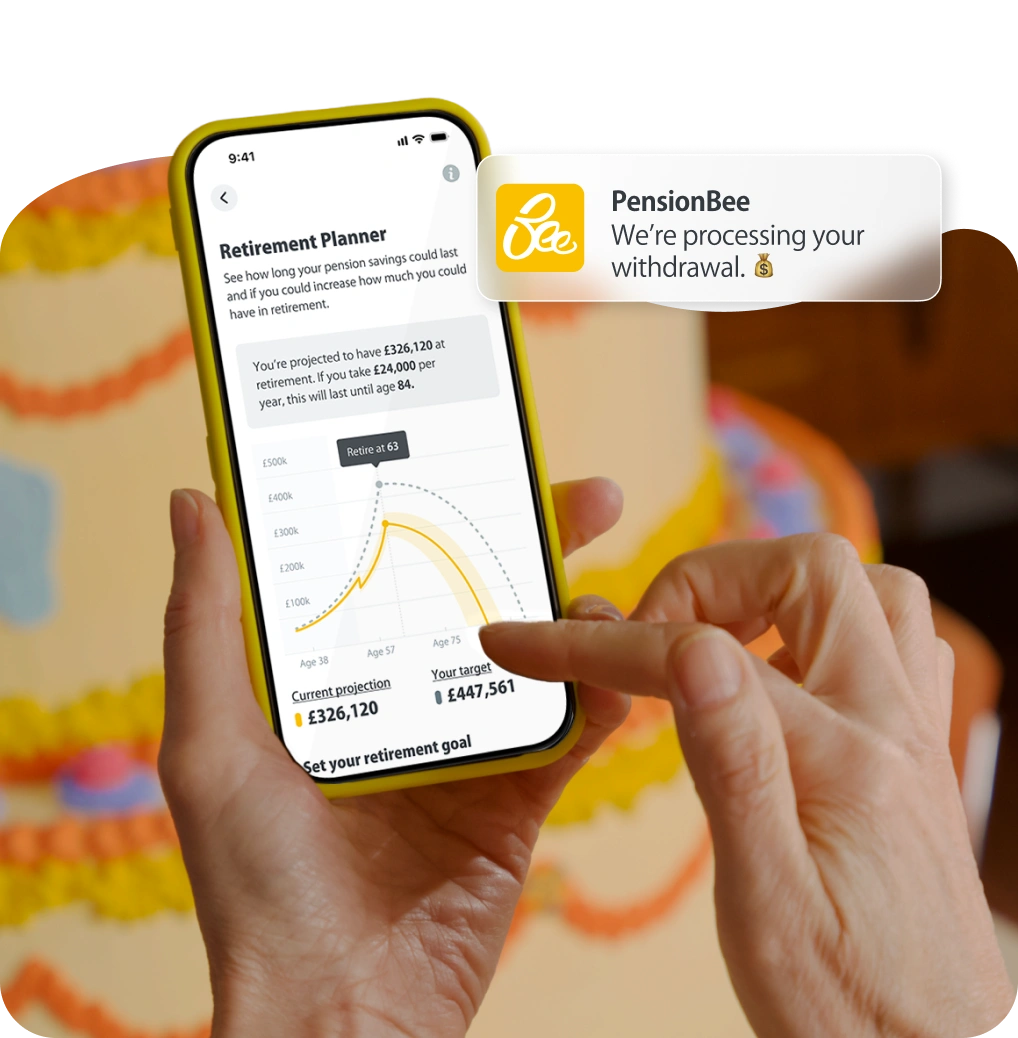
The Pension Calculator gives you a clearer idea of how much your savings could be worth by the time you reach retirement. To get your forecast, use the sliders or live edit the fields with:
Your current age
The age you’d like to retire
The amount you’d like to retire with, or the monthly income you’d like in retirement
Your current pension pot
Monthly contributions from you and your employer
You can also download your projection as a PDF and compare it against the Retirement Living Standards, which can help picture your life in retirement.
Understanding your forecast
The yellow line is your current projection. It shows how your pot could grow until you retire, and then how long it could last once you start drawing an income. The blue dotted line is your target. It shows the pot you’d need to pay your desired income until age 100, allowing for a long retirement.
You can also see the impact of:
Taking 25% tax-free cash: your pot drops by a quarter (at age 55, or 57 from 2028) and grows from a smaller base after that.
Including the full new State Pension: from State Pension age (67) it pays some or all of your income, so your pot needs to pay out less and could last longer.
Investment growth rates of 3%, 5% or 8%: compare illustrations of low, average and high annual growth.
Assumptions behind your projection
The solid yellow line shows your current projection, which assumes investment growth of 5% every year. You can use the toggles below your projection to change the investment growth and choose from 3% (low), 5% (average) or 8% (high). We’ve assumed inflation of 2.5% per year and an annual management fee of 0.7% taken from your pension each year. We've also assumed that your monthly contributions rise in line with inflation, so that they keep the same value in today’s money. When using the personal monthly or one-off contribution sliders, your projection will include the 25% tax top up from HMRC.
If you include the State Pension, we’ve assumed you’ll get the full new State Pension (which usually needs 35 qualifying years of National Insurance) and that it rises in line with inflation. We’ve used a State Pension age of 67. Under current law it’s due to rise to 68 between 2044 and 2046 for people born on or after 6 April 1977, and this could change.
Are you on track for your dream retirement?
Here's what Pension UK's Retirement Living Standards say.
The Retirement Living Standards show how much you might need each year to enjoy a Minimum, Moderate or Comfortable standard of living in retirement. Explore the living standards below to see examples of everyday costs and what your retirement could look like.
Single personCouple
These figures assume you’re mortgage and rent-free.
Pension Calculator FAQs
What are the projection assumptions?
Why do we include an assumed rate of inflation?
What is the difference between personal and business account contributions?
How does taking a 25% tax-free amount work?
What are the State Pension assumptions?
How have you worked out my average life expectancy?
What should my desired retirement income be?
Combine your old pension pots into one new easy-to-manage plan. It takes just a few minutes to sign up.