Inflation Calculator
How far will your savings go in retirement?
A rise in inflation happens when the price of goods such as food, transport and living costs, like electricity, rise. Changes to inflation not only impact what you can afford today but also what you can afford in the future. Savings like your pension aren’t immune to these changes and if your pension value remains the same, this decreases your purchasing power in the future, which over time could mean that your pension savings might not get you as far as you’d hoped.
How far could your pension take you in retirement?
Use our Inflation Calculator to find out how your pension could be impacted.
What is inflation?
Inflation is the rate at which the cost of everyday things like food, transport and electricity increases over time. The rise in prices, often presented as a percentage, means that a unit of money essentially buys less than it did previously. Over time, this reduces your purchasing power as your money doesn’t spread as far as before.
For example, if you buy a pint of milk for £1 today and inflation jumps to 10%, next year the same pint will cost you £1.10, and then if inflation sticks at 10%, it will cost you £1.21 the year after.The effect of inflation is most noticeable when you’re looking at large sums of money, such as your pension pot. For example, if your pension pot is worth £50,000 today, to keep up with inflation and maintain the same purchasing power in 10 years time, with an assumed inflation rate of 2.5% per year, you’d need to have £64,004.23 in your pot. This means over those 10 years you’d need to either contribute or have investment growth of an additional £14,004.23 in order to have the same purchasing power as today.
For example, if you buy a pint of milk for £1 today and inflation jumps to 10%, next year the same pint will cost you £1.10, and then if inflation sticks at 10%, it will cost you £1.21 the year after.The effect of inflation is most noticeable when you’re looking at large sums of money, such as your pension pot. For example, if your pension pot is worth £50,000 today, to keep up with inflation and maintain the same purchasing power in 10 years time, with an assumed inflation rate of 2.5% per year, you’d need to have £64,004.23 in your pot. This means over those 10 years you’d need to either contribute or have investment growth of an additional £14,004.23 in order to have the same purchasing power as today.
How could inflation impact my pension pot value?
The effect of inflation is most noticeable when you’re looking at large sums of money, such as your pension pot. For example, if your pension pot is worth £50,000 today, to keep up with inflation and maintain the same purchasing power in 10 years time, with an assumed inflation rate of 2.5% per year, you’d need to have £64,004.23 in your pot. This means over those 10 years you’d need to either contribute or have investment growth of an additional £14,004.23 in order to have the same purchasing power as today.
Input your details below to find out how inflation could impact your pension pot. These calculations are for illustrative purposes only.
Input your details below to find out how inflation could impact your pension pot. These calculations are for illustrative purposes only.
See how inflation will impact your pension value
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.

The calculator assumes investment growth of 5% and pension fees of 0.7% each year. Investment returns aren’t guaranteed.

Your current pension pot of £50,000 could be worth
£116,053
with 5% investment growth in 2071 if you continue to contribute £1 per year.
The net effect of 0.3% inflation means that your pot would be worth £3,037,538 in 2071 in today's money. To have the same purchasing power as today, you'd need to either contribute or have investment growth of an additional £430,353.
The net effect of 0.3% inflation means that your pot would be worth £3,037,538 in 2071 in today's money. To have the same purchasing power as today, you'd need to either contribute or have investment growth of an additional £430,353.
Pension Pot
The total estimated value of your pension pot excluding net inflation
Today's Money
The total estimated value of your pension pot including net inflation
The cost of living with 1.0% inflation rate
A pint of milk
2071
£1.47
A pint of beer
2071
£1.47
A litre of petrol
2071
£1.47
A loaf of bread
2071
£1.47
1 month’s rent
2071
£1.47
As always with investments, your capital is at risk. The value of your investment can go down as well as up, and you may get back less than you invest. This information should not be regarded as financial advice.
Are you on track for your dream retirement?
Here's what Pension UK's Retirement Living Standards say.
The Retirement Living Standards show how much you might need each year to enjoy a Minimum, Moderate or Comfortable standard of living in retirement. Explore the living standards below to see examples of everyday costs and what your retirement could look like.
Inflation Calculator FAQs

What causes inflation?
What is the projected rate of inflation?
How do raising inflation rates affect pension funds?
How much income do I need in retirement?
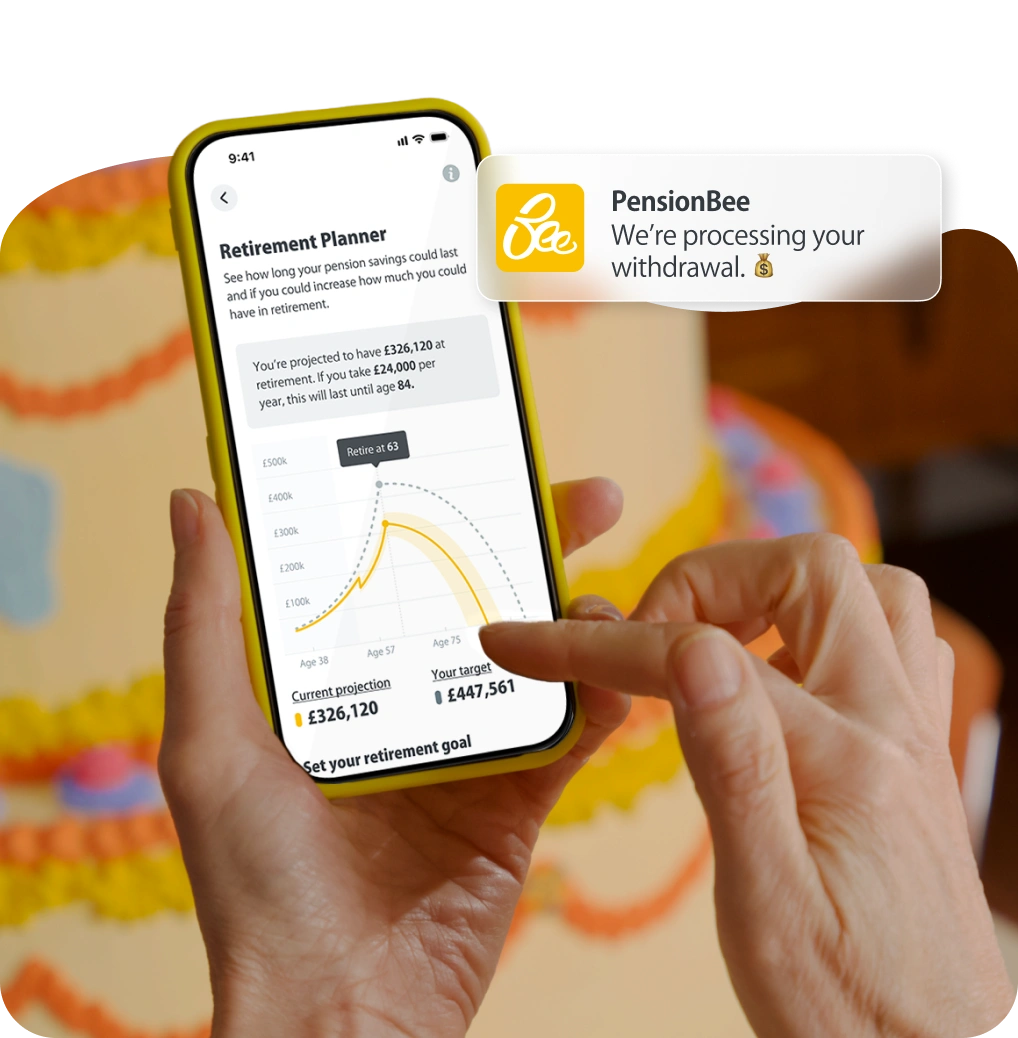
Combine your old pension pots into one new easy-to-manage plan. It takes just a few minutes to sign up.
Who could you be with PensionBee?
PensionBee is authorised and regulated by the Financial Conduct Authority.
With pensions, your capital is at risk.
With pensions, your capital is at risk.


General enquiries: 020 3457 8444
General enquiries: contact@pensionbee.com
Press: press@pensionbee.com
Partners: partnership@pensionbee.com
© Copyright 2026 PensionBee Ltd. Company registration: 9354862. FCA Reference Number: 744931. Information Commissioner's Office registration: ZA131262. We use cookies to ensure that you get the best possible experience. By continuing to use our website you are agreeing to their use. Find out more about cookies.
PensionBee is authorised and regulated by the Financial Conduct Authority.
With pensions, your capital is at risk.
With pensions, your capital is at risk.

Why PensionBee?
About us
Calculators
Help & Knowledge

General enquiries: 020 3457 8444
General enquiries: contact@pensionbee.com
Press: press@pensionbee.com
Partners: partnership@pensionbee.com
© Copyright 2026 PensionBee Ltd. Company registration: 9354862. FCA Reference Number: 744931. Information Commissioner's Office registration: ZA131262. We use cookies to ensure that you get the best possible experience. By continuing to use our website you are agreeing to their use. Find out more about cookies.