The 2027 Contribution Limits: Are You Leaving Tax Savings on the Table?
How to Save for Retirement With Irregular Income: A SEP IRA Guide for the Self-Employed
What is RetireBy and How Does it Calculate Your Retirement Number?
One Open Enrollment Move That Isn't on Your Benefits Form
Mid-Year Retirement Planning Checklist: 5 Questions to Ask Yourself About Your 401(k)
"I Didn't Realize How Much It Was Weighing on Me": 5 People on What It Felt Like to Finally Get Their Retirement Savings in Order
The 401(k) You Forgot About is Costing You More Than You Think
The Retirement Gap Women Can’t Ignore
Millennials and Gen X Are Underestimating How Long Retirement Will Last
Tax Season Checklist
Year-End Retirement Checklist
Catch-Up Contributions for 401(k)s and IRAs Explained
401(k) Rollover Checklist
Year-End Retirement Tax Strategies
401(k) Explained: Everything You Need to Know Before Your Next Job
IRA and 401(k) Deadlines
What Caregivers Can Do to Close the Retirement Gap
401(k) vs IRA? Side-by-Side Comparison
What IRA is Best for a Self-Employed Person?
A Simple Guide on IRA Contribution Reporting
A Comprehensive Guide to Traditional and Roth IRAs
The 2027 Contribution Limits: Are You Leaving Tax Savings on the Table?
The IRS has announced the 2027 401(k) and IRA limits. Here’s what changed, which account fits your income, and how to put the new limits to work toward your retirement goals.
At a glance
The IRS announced the 2027 retirement contribution limits on November 12, 2026. The 2027 IRA limit is $7,500 or, $8,600 if you’re 50 or older.
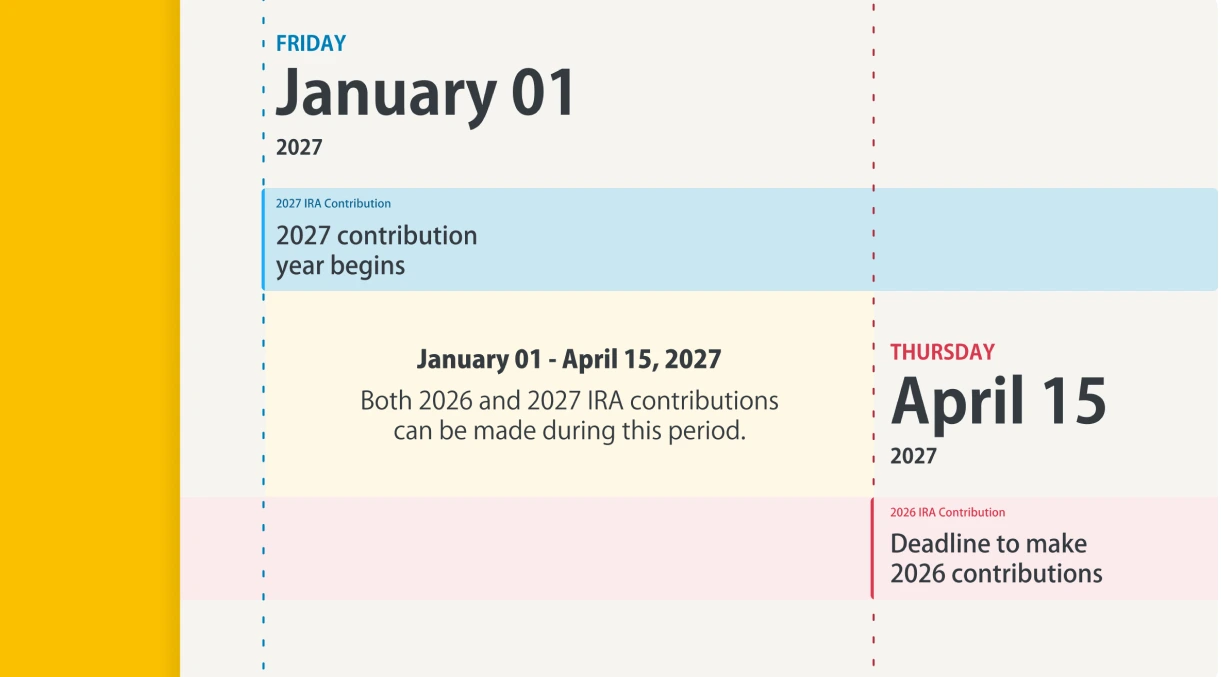
From January 1 to April 15, 2027, you can contribute toward both your 2026 and 2027 IRA limits if you have not already maxed out your contribution for 2026.
SEP IRA owners have until their tax filing deadline, including extensions, to fund the prior year.
The 2027 401(k) limit rises to $25,500, with an $8,500 catch-up if you’re 50 or older.
Setting up monthly contributions can help spread your savings across the year instead of leaving a lump sum for the deadline.
The IRS kept the IRA contribution limit for 2027 at $7,500 or, $8,600 if you’re 50 or older. If you haven’t maxed out your 2026 IRA yet, you have until April 15, 2027 to do it. That means early 2027 is a rare window when you can fund two tax years at once.
When Is the Deadline for 2026 IRA Contributions?
You have until April 15, 2027 to make IRA contributions that count toward 2026. That’s your tax filing deadline, and a filing extension doesn’t extend it for Traditional or Roth IRAs.
Workplace 401(k) contributions work differently. They come out of your paycheck, so they have to be made by December 31 of the year in which you contribute in.
If you’re self-employed, you can generally make 2026 SEP IRA contributions up to your business’s tax filing deadline. If you get a filing extension, that deadline is extended too.
Contributing before the deadline helps give your money more time to grow. If your Traditional IRA contribution is deductible, you can subtract the amount you contributed from your income when you file your 2026 tax return. That means you pay tax on a smaller amount of income, which can lower your 2026 tax bill.
What Are the 2027 Contribution Limits?
The IRS announced its 2027 cost-of-living adjustments on November 12, 2026. Here’s how the new limits compare with 2026.
The IRA limit covers your Traditional and Roth IRAs together, not each one. You also can’t contribute more than your earned income for the year.
The Deadline That Matters
Every year, the IRS reviews retirement account contribution limits to adjust them for inflation. While workplace 401(k) contributions must be locked in for the year by December 31st, IRAs offer a much longer window.
You typically have until April 15th of the following year to make contributions that count toward your previous tax year.
This creates a unique, high-value window. If you haven't maxed out your previous year's contribution limits, adding to your account in this window can help give your money more time to compound and potentially lower your taxable income.
Be Retirement Confident.
Roll over all your old 401(k)s into a PensionBee Individual Retirement Account (IRA). It takes just a few minutes to sign up.
Each type of IRA is taxed differently, and some are built for specific situations. Here's a quick guide to which one might suit you.
Traditional IRA. Contributions may be tax-deductible now, depending on your income and whether you or your spouse has a retirement plan at work. You pay income tax when you withdraw in retirement.
Roth IRA. You contribute after-tax dollars, and qualified withdrawals in retirement are tax-free. Roth IRAs have income limits: if your modified adjusted gross income falls in the 2027 phase-out range ($158,000 to $173,000 for single filers and heads of household, or $250,000 to $260,000 for married couples filing jointly), the amount you can contribute directly shrinks or disappears.
SEP IRA. Built for freelancers, consultants and small business owners. You can contribute up to 25% of compensation, subject to an annual dollar cap, which makes it a powerful way for self-employed people to save more and help reduce their taxable income.
You don't have to pick just one. You can split contributions between a Traditional and a Roth IRA, as long as the combined total stays within the annual limit. And if you have self-employment income, a SEP IRA can sit alongside either.
Three IRA moves to consider before April 15
Check your true gap. Add up what you've contributed to your IRA for 2026 and compare it against the IRA limit. Then you'll know about how much room you have left. If you have the financial capacity, consider topping it up before the deadline.
Automate your 2027 IRA savings. Divide the new IRA limit by 12 and set up monthly contributions. When saving happens on autopilot, there's no year-end lump sum to worry about.
Audit your tax eligibility. If your household income changed significantly, check whether a deductible Traditional IRA contribution or a Roth IRA gives you the bigger advantage. Then plug your plan into our RetireBy calculator to see how maxing out your IRA contributions could affect your retirement goals.
The Cost of Doing Nothing
One of the biggest threats to your retirement savings often isn't the market. It's inertia.
Jason, a PensionBee customer from New York assumed the retirement accounts he'd left at old jobs were fine on their own. A decade passed before he checked. He found his money had been moved into a low-yield cash default and worn down by fees.
"Ignorance made me comfortable," Jason says. "I truly believed it was safe. And I was sadly wrong."
Bring It All Together in 30 Minutes
Have old 401(k)s or IRAs from past employers scattered? Consolidating them shouldn't be a bureaucratic headache. Erin, a PensionBee customer from Texas who’s a financial consulting professional, used a dedicated PensionBee BeeKeeper to seamlessly locate and roll over three separate accounts in under 30 minutes.
The new limits are here. Don't let April 15 pass without knowing where you stand.
Investing involves risk.
This post, and any associated customer testimonial or third party endorsement, is provided solely for informational and educational purposes, should not be taken as tax, legal, financial or investment advice and is not an offer, solicitation, or recommendation to buy or sell any securities or investments.
The RetireBy Calculator estimates a retirement savings target based on your inputs (such desired retirement location and lifestyle and current savings) and our assumptions (including investment growth, inflation, and Social Security benefits). Results are hypothetical, not guaranteed, and may differ significantly from your actual needs. The calculator does not consider all your personal circumstances or replace individualized financial planning.
Investing involves risk. Past performance is no guarantee of future results. Not bank guaranteed. Not FDIC insured.
No Solicitation, Recommendation or Warranties Information provided directly by PensionBee or on PensionBee’s behalf, whether via direct communications from PensionBee, publicly accessible pages of https://www.PensionBee.com/us (including when accessed via the PensionBee app), PensionBee advertising and sponsorships, PensionBee’s direct and sponsored social media, or otherwise, in each case including any associated customer testimonial or third party endorsement and any information prepared by any unaffiliated third party or link to any third party source (collectively, “PensionBee Materials”) is provided solely for informational and educational purposes.
PensionBee Materials do not constitute tax, legal, financial or investment advice or an offer, solicitation or recommendation to buy or sell any securities or investments.
PensionBee Materials do not consider any individual investors’ specific financial, legal or tax situation, objectives, risk tolerance, or investment needs.
PensionBee Inc. does not make any representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of, and takes no responsibility for, any PensionBee Materials.
*Product images, figures, and projections used are hypothetical, for marketing purposes only, and do not represent actual customer returns.
Where PensionBee customers are featured, each has received a one-time cash payment for their testimonial. Testimonials reflect individual customer experiences and may not be representative of all PensionBee Customers.
Options on Rollovers A rollover is not your only option for an old 401(k) or IRA, you may alternatively decide to leave your assets with your former employer, rollover your plan to a new employer or to cash in your old plan with the resulting tax penalties applied. PensionBee Inc. does not provide tax advice or individual recommendations as to which of these options is most appropriate for your individual circumstances. To understand the implications of each of the options available to you and help you decide between them you may wish to consult a tax professional and or your financial advisor who has knowledge of your individual circumstances. For more information see FINRA - Retirement Accounts.
Our collaboration with State Street Global Advisors State Street Global Advisors is not involved in the management of the strategies and accounts offered to you by PensionBee. State Street Global Advisors and its affiliates are not your investment adviser and are not a fiduciary with respect to you or your account. PensionBee is independent of State Street Global Advisors. State Street Global Advisors is not recommending or endorsing PensionBee or making a determination of the suitability or appropriateness for any individual products or investment strategies offered by PensionBee, including those described herein.
The SPDR® S&P500 ETF®, SPDR® S&P MIDCAP 400® ETF, SPDR® Dow Jones Industrial Average ETF are exchange traded funds with the investment objective to correspond to the price and yield performance of the S&P 500® Index, S&P®MidCap 400®IndexTM and Dow Jones Industrial AverageSM. The shares of the SPDR® S&P 500® ETF, S&P MIDCAP 400® ETF, SPDR® Dow Jones® Industrial Average ETF represent individual ownership interest in the Trust’s portfolio.
The whole or any part of this work may not be reproduced, copied or transmitted or any of its contents disclosed to third parties without SSGA's express written consent.
ETFs trade like stocks, are subject to investment risk, fluctuate in market value and may trade at prices above or below the ETFs net asset value. Brokerage commissions and ETF expenses will reduce returns.
The S&P 500® Index is a product of S&P Dow Jones Indices LLC or its affiliates (“S&PDJI”) and have been licensed for use by State Street Global Advisors. S&P®, SPDR®,S&P 500®, US 500 and the 500 are trademarks of Standard & Poor’s Financial Services LLC (“S&P”); Dow Jones® is a registered trademark of Dow Jones Trademark Holdings LLC (“Dow Jones”) and has been licensed for use by S&P Dow Jones Indices; and these trademarks have been licensed for use by S&P DJI and sublicensed for certain purposes by State Street Global Advisors. The fund is not sponsored, endorsed, sold or promoted by S&P DJI, Dow Jones, S&P, their respective affiliates, and none of such parties make any representation regarding the advisability of investing in such product(s) nor do they have any liability for any errors, omissions, or interruptions of these indices.
Distributor: State Street Global Advisors Funds Distributors, LLC, member FINRA, SIPC, an indirect wholly owned subsidiary of State Street Corporation. References to State Street may include State Street Corporation and its affiliates. Certain State Street affiliates provide services and receive fees from the SPDR ETFs.
ALPS Distributors, Inc., member FINRA, is distributor for SPDR® S&P 500®, SPDR® S&P MidCap 400® and SPDR® Dow Jones Industrial Average, all unit investment trusts. ALPS Distributors, Inc. is not affiliated with State Street Global Advisors Funds Distributors, LLC.
Before investing, consider the funds' investment objectives, risks, charges and expenses. To obtain a prospectus or summary prospectus which contains this and other information, call 1-866-787-2257 or visit https://www.statestreet.com/im. Read it carefully.
Website Cookies We use cookies and similar technologies to enable our website to function, understand how our website is used, and support advertising and marketing activities. You can manage your cookie preferences at any time through our Manage My Cookies settings. Disabling advertising cookies may prevent certain advertising, retargeting, and cross-site tracking technologies from being used and may impact some website functionality and personalised content. Where required by applicable law, we recognise browser-based opt-out preference signals, including Global Privacy Control (GPC), and will automatically disable advertising and cross-context behavioural advertising cookies for that browser or device where applicable. For more information about how we collect and use personal information, please see our Privacy Policy.
Trust Pilot Scores Trustpilot is a consumer review platform. Trustpilot scores shown in PensionBee Materials are a result of reviews collected from PensionBee customers in the UK between 2016 and 2026 scoring PensionBee’s UK pension products. Customers were not compensated to give a review. The score has always been 4.5 or higher.
SEC Registration PensionBee Inc. is registered with the SEC as an investment adviser (CRD # 331741/SEC#: 801-130697). A copy of PensionBee Inc. 's Brochure containing our written disclosure statement discussing our business operations, services, and fees, is available at the SEC’s investment adviser public information website – https://www.adviserinfo.sec.gov or from us.
PensionBee Inc. (Delaware Registration Number SR20241105406) is located on 85 Broad Street, New York, NY 10004.